Last Updated on November 17, 2026 by Team TBH
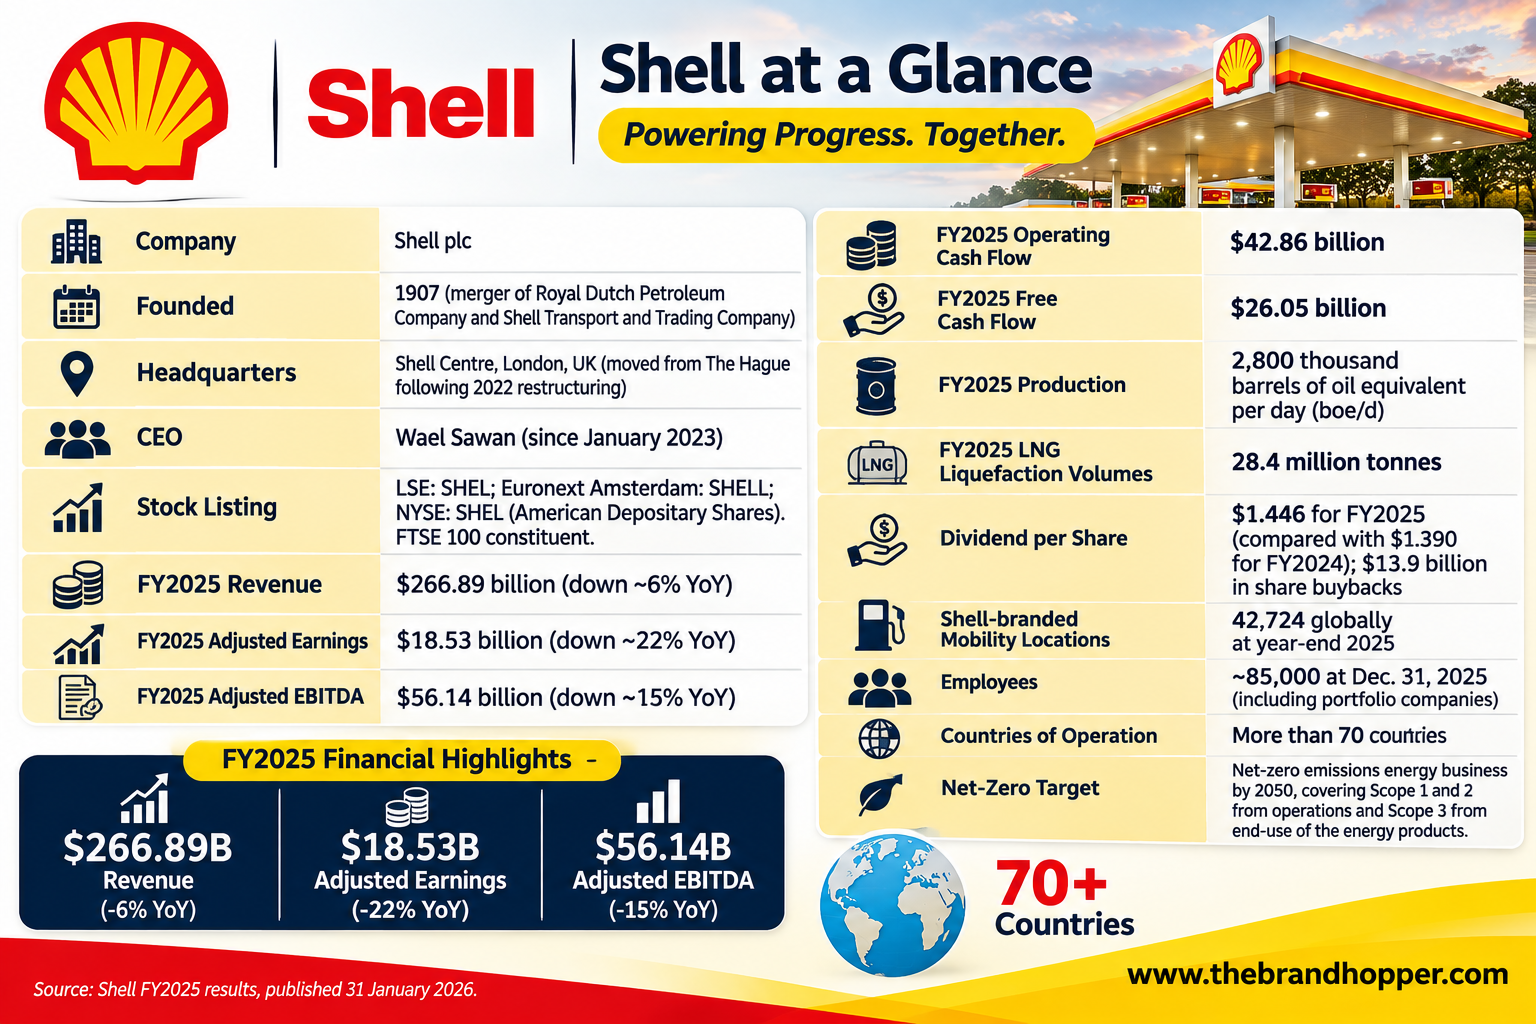
Shell plc is one of the world’s largest integrated energy companies, operating across oil and gas exploration, liquefied natural gas (LNG), refining, chemicals, trading, and energy marketing. The company was formed in 1907 through the combination of the Royal Dutch Petroleum Company and the Shell Transport and Trading Company.
In January 2022, Shell simplified its corporate structure, moved its tax residence and headquarters to the United Kingdom, and changed its name from Royal Dutch Shell plc to Shell plc. Today, it operates in more than 70 countries and remains a major force in global energy markets.
Shell’s portfolio includes a substantial LNG business, upstream oil and gas production, refining and chemicals operations, and a global mobility network. According to its 2025 company figures, Shell produced approximately 2.8 million barrels of oil and gas per day, sold 73 million tonnes of LNG, and served around 29 million customers daily at Shell-branded mobility sites.
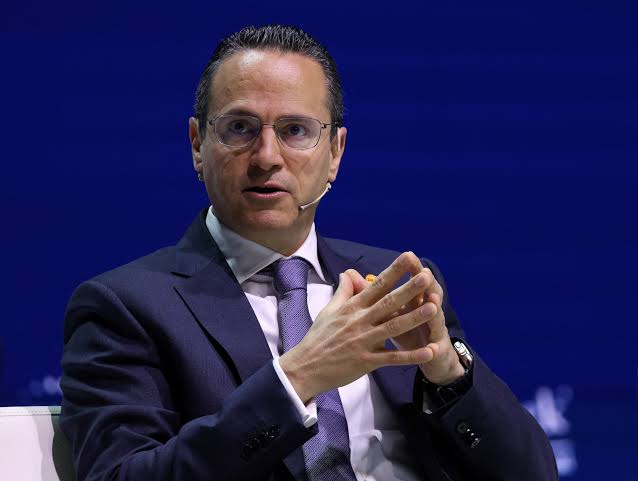
Under CEO Wael Sawan, who became chief executive in January 2023, Shell has focused on operational performance, capital discipline, and improving returns from its core businesses. Its strategy prioritizes integrated gas and LNG, upstream production, and selective investment in lower-carbon energy and customer-facing businesses.
Shell’s strategy has also involved portfolio simplification and the sale or restructuring of businesses that do not meet its financial and strategic priorities. The company’s approach is therefore not simply to expand renewable energy capacity, but to focus on businesses where it believes it can generate competitive returns.
Shell’s latest completed financial year, 2025, produced adjusted earnings of $18.5 billion, compared with $23.7 billion in 2024. Cash flow from operating activities was $42.9 billion, while free cash flow stood at $26.1 billion. These results demonstrate the impact of commodity prices, refining margins, trading performance, and operational conditions on the company’s financial performance.
Shell’s competitive environment includes international oil and gas companies such as ExxonMobil, BP, TotalEnergies, and Chevron. State-owned energy companies such as Saudi Aramco, PetroChina, Sinopec, and Petrobras also compete with Shell for resources, customers, infrastructure, and investment.
Other competitors operate in more specialized areas, including independent exploration and production, refining, chemicals, and renewable fuels. The 17 companies profiled below represent the breadth of Shell’s competitive landscape.
Top 17 Competitors and Alternatives of Shell
The following companies compete with Shell across different parts of the energy value chain. Their latest financial performance, business models, and strategic priorities provide a useful comparison of the competitive environment in which Shell operates.
| Competitor | Latest Revenue / Sales (FY2025) | Headquarters |
|---|---|---|
| ExxonMobil | ~$323.9 billion in sales and operating revenue | Spring, Texas, USA |
| BP | See FY2025 annual report; underlying RC profit was $7.5 billion | London, UK |
| Chevron | ~$184.4 billion | Houston, Texas, USA |
| TotalEnergies | See FY2025 annual results | Courbevoie, France |
| Saudi Aramco | See FY2025 annual report; net income was ~$105 billion | Dhahran, Saudi Arabia |
| PetroChina | RMB 2.86 trillion | Beijing, China |
| Sinopec | RMB 2.78 trillion | Beijing, China |
| Equinor | See FY2025 annual results | Stavanger, Norway |
| Petrobras | ~$89.2 billion | Rio de Janeiro, Brazil |
| ConocoPhillips | Upstream-focused revenue; see FY2025 annual report | Houston, Texas, USA |
| Eni | €82.2 billion in sales from operations | Rome, Italy |
| Repsol | See FY2025 annual results | Madrid, Spain |
| CNOOC | See FY2025 annual results | Beijing, China |
| Occidental Petroleum | ~$21.6 billion in net sales | Houston, Texas, USA |
| Valero Energy | ~$122.7 billion | San Antonio, Texas, USA |
| Phillips 66 | See FY2025 annual report | Houston, Texas, USA |
| Reliance Industries | ₹11.76 trillion in gross revenue (FY2026) | Mumbai, India |
Note: Financial figures are based on each company’s latest completed financial year available by November 2026. Reporting periods, accounting definitions, currencies, and business models differ. Revenue should not be interpreted as a direct measure of profitability or competitive strength.
1. ExxonMobil
ExxonMobil is one of Shell’s most direct competitors and one of the world’s largest publicly traded integrated oil and gas companies. Its operations span upstream production, LNG, refining, chemicals, fuels marketing, and lower-emission technologies.
ExxonMobil reported full-year 2025 earnings of approximately $28.8 billion, compared with $33.7 billion in 2024. Sales and other operating revenue reached approximately $323.9 billion, while cash flow from operations was $52 billion.
A major development in ExxonMobil’s recent history was its $60 billion acquisition of Pioneer Natural Resources, completed in May 2024. The transaction substantially strengthened its position in the Permian Basin and expanded its exposure to one of the most productive oil and gas regions in the United States.
ExxonMobil’s production averaged approximately 4.7 million barrels of oil equivalent per day in 2025. This was considerably higher than Shell’s approximately 2.8 million barrels per day, giving ExxonMobil a significant scale advantage in upstream production.
The company also has a substantial refining and chemicals business. Its global operations compete with Shell for crude oil supplies, LNG customers, industrial chemicals buyers, and retail fuel demand.
ExxonMobil has invested in carbon capture and storage, hydrogen, and lower-emission fuels through its Low Carbon Solutions business. Its Baytown hydrogen and carbon capture projects are part of its strategy to develop commercial-scale lower-emission energy solutions.
2. BP (British Petroleum)
BP is one of Shell’s closest competitors among the European integrated energy companies. Both businesses operate across upstream oil and gas, LNG, refining, trading, lubricants, and customer-facing energy services.
BP reported underlying replacement cost profit of approximately $7.5 billion for 2025, compared with $8.9 billion in 2024. Its oil and gas production averaged approximately 2.3 million barrels of oil equivalent per day.
The company has been reshaping its strategy to strengthen financial performance and simplify its portfolio. Its priorities include improving returns from oil and gas, reducing costs, and directing investment toward businesses with stronger commercial prospects.
BP’s leadership has also changed. Carol Howle served as interim CEO during the transition following Murray Auchincloss, while Meg O’Neill was scheduled to take over as CEO in April 2026.
BP competes with Shell in the lubricants market through Castrol, which is one of the most recognized brands in automotive and industrial lubricants. Shell’s Helix and industrial lubricants businesses compete for similar customers and distribution channels.
The two companies also compete in LNG, refining, fuel retail, and electric vehicle charging. BP operates its BP Pulse charging network, while Shell has developed its own public charging infrastructure.
BP has moderated its earlier renewable energy ambitions and is placing greater emphasis on financial discipline and returns. This makes its strategy increasingly focused on balancing conventional energy operations with selected lower-carbon businesses.
3. Chevron
Chevron is a major US-based integrated energy company and one of Shell’s most important global competitors. Its operations include oil and gas production, LNG, refining, chemicals, fuels marketing, and emerging lower-carbon energy businesses.
Chevron reported 2025 sales and other operating revenues of approximately $184.4 billion. Net income attributable to Chevron was approximately $12.3 billion, compared with $17.7 billion in 2024.
The company’s acquisition of Hess Corporation strengthened its international upstream portfolio, particularly through its interest in Guyana’s Stabroek Block. Chevron completed the acquisition in 2025 after resolving the arbitration dispute involving ExxonMobil’s pre-emption rights.
Chevron’s position in the Permian Basin is another major competitive advantage. The company has continued expanding production in the region while developing its international portfolio in the Gulf of Mexico, Kazakhstan, Australia, and other markets.
Its Australian LNG projects, including Gorgon and Wheatstone, compete with Shell’s LNG portfolio for customers across Asia. Both companies also compete for long-term gas supply contracts and opportunities in emerging LNG markets.
Chevron has expanded its investments in carbon capture, hydrogen, and renewable fuels. However, its approach has generally emphasized commercial viability and returns rather than pursuing renewable energy capacity at the same scale as some European energy companies.
4. TotalEnergies
TotalEnergies is a major French integrated energy company and one of Shell’s closest European competitors. Its operations cover oil and gas production, LNG, refining, chemicals, electricity, renewable power, and energy marketing.
The company reported adjusted net income of approximately $15.6 billion for 2025, down around 15% from the previous year. Its cash flow remained resilient, supported by production growth and the performance of its integrated businesses.
TotalEnergies has developed a substantial renewable electricity portfolio, including solar and wind power projects across Europe, the Americas, Africa, and Asia. Its integrated electricity business is a major part of its long-term strategy.
The company has also expanded its LNG portfolio through investments and partnerships in Qatar, Mozambique, Papua New Guinea, and the United States. These operations compete directly with Shell for international gas customers and long-term LNG contracts.
TotalEnergies is particularly relevant to Shell because it competes across both conventional and lower-carbon energy markets. Its electricity and renewable power operations provide a broader comparison with Shell’s efforts to build a more diversified energy portfolio.
The company’s strategy combines investment in oil and gas production with expansion in electricity, renewable power, and customer energy services. This positions TotalEnergies as one of the most diversified competitors among the European supermajors.
5. Saudi Aramco
Saudi Aramco is one of the world’s largest integrated energy companies and a major competitor to Shell in crude oil production, refining, chemicals, and international energy markets. Unlike Shell, Aramco is majority-owned by the Saudi Arabian government and operates with access to some of the world’s lowest-cost conventional oil resources.
Aramco reported net income of approximately $104.7 billion for 2025. Its operating cash flow was approximately $136.2 billion, while free cash flow reached around $85.4 billion.
The company’s upstream operations benefit from large conventional oil reserves and relatively low production costs. This gives Aramco a significant competitive advantage in crude oil markets, particularly when global prices weaken.
Aramco has also been expanding its downstream and chemicals businesses. Its investments in refining and petrochemicals across Asia and the Middle East are designed to increase the value generated from its hydrocarbon production.
The company has pursued international partnerships and investments in China, South Korea, and other markets. Its participation in refining and chemicals projects allows it to compete more directly with integrated energy companies such as Shell.
Aramco’s scale, access to resources, and state ownership make it a fundamentally different competitor from publicly traded international oil companies. Its financial strength and production capacity give it considerable influence in global energy markets.
6. PetroChina
PetroChina is one of China’s largest integrated oil and gas companies and the publicly listed subsidiary of China National Petroleum Corporation (CNPC). Its business includes exploration and production, refining, chemicals, natural gas, pipelines, and fuel marketing.
PetroChina reported 2025 revenue of approximately RMB 2.86 trillion. The company operates across the entire energy value chain, making it a competitor to Shell in upstream production, LNG, gas distribution, refining, and chemicals.
Natural gas is an important part of PetroChina’s business. Its domestic production, pipeline infrastructure, and gas distribution operations give it a strong position in China’s energy market.
The company also operates through Kunlun Energy, which is involved in natural gas distribution, LNG, and related infrastructure. These operations compete with international suppliers and energy companies seeking access to China’s growing gas market.
PetroChina’s refining and chemicals businesses are among the largest in the world. Its operations compete with Shell’s refining and chemicals facilities for regional customers, feedstock, and market share.
The company’s state-owned parent and strong domestic infrastructure provide significant advantages in China. Shell nevertheless maintains partnerships and investments in the country, particularly in chemicals, lubricants, and energy-related businesses.
7. Sinopec (China Petroleum & Chemical Corporation)
Sinopec is one of the world’s largest integrated energy and chemicals companies. It competes with Shell particularly in refining, petrochemicals, fuel marketing, hydrogen infrastructure, and industrial energy supply.
Sinopec reported 2025 revenue of approximately RMB 2.78 trillion, down around 9.5% from 2024. Profit attributable to shareholders was approximately RMB 32.5 billion, reflecting pressure from lower petroleum and petrochemical product prices.
The company’s refining operations give it a substantial presence in the global downstream energy market. Its refineries process crude oil into gasoline, diesel, aviation fuel, and other products, while its chemicals operations supply industrial customers across China and international markets.
Sinopec’s large domestic retail network is another competitive advantage. Its service stations and distribution infrastructure provide extensive access to Chinese fuel customers, where Shell also operates through selected partnerships and investments.
The company has been investing in hydrogen production, refueling infrastructure, and other lower-carbon energy technologies. It is also developing projects related to green hydrogen and renewable energy as China expands its energy transition efforts.
Sinopec’s scale in refining, chemicals, and fuel distribution makes it a particularly important competitor for Shell in Asia. Its state-owned structure and access to China’s domestic market also provide advantages that international energy companies cannot easily replicate.
8. Eni
Eni is an Italian integrated energy company that competes with Shell in exploration and production, LNG, refining, chemicals, and lower-carbon energy. Its operations are concentrated across Europe, Africa, the Middle East, and other international markets.
Eni reported sales from operations of approximately €82.2 billion in 2025. Its adjusted net profit attributable to shareholders was approximately €5 billion, while reported net profit was around €2.6 billion.
One of Eni’s distinctive strategic features is its satellite business model. The company has developed separately managed businesses such as Plenitude, which focuses on renewable power and retail energy, and Enilive, which focuses on mobility and lower-carbon fuels.
Plenitude operates in renewable electricity generation, energy retail, and electric vehicle charging. These activities compete with Shell’s electricity retail, renewable energy, and mobility businesses in European markets.
Eni is also a significant player in LNG and natural gas production. Its international gas portfolio and African projects compete with Shell for long-term gas customers and supply opportunities.
The company has invested in biofuels and biorefineries through Enilive. Its renewable diesel and sustainable aviation fuel activities are particularly relevant to Shell’s efforts to develop lower-carbon transportation fuels.
9. ConocoPhillips
ConocoPhillips is one of the world’s largest independent exploration and production companies. Unlike Shell, it focuses primarily on upstream oil and gas rather than operating a large integrated refining, chemicals, and retail business.
The company reported full-year 2025 earnings of approximately $8 billion. Its acquisition of Marathon Oil, completed in November 2024, strengthened its position in the United States and expanded its production portfolio.
ConocoPhillips operates across several important production regions, including the Permian Basin, Eagle Ford, Bakken, Alaska, Norway, and Australia. Its portfolio includes conventional, unconventional, and LNG-linked natural gas assets.
The company’s Willow project in Alaska is a major long-term development. The project is expected to contribute substantial production once fully developed, although its output will depend on construction, commissioning, and operating schedules.
ConocoPhillips competes with Shell for upstream acreage, exploration opportunities, engineering resources, and investment capital. Its focused business model allows it to direct most of its capital and operational expertise toward maximizing returns from oil and gas production.
Because it does not operate a comparable global retail and refining network, ConocoPhillips is a more specialized competitor than ExxonMobil or Chevron. Its importance to Shell is concentrated primarily in exploration, production, and natural gas.
10. Equinor
Equinor is a Norwegian state-controlled energy company and a major competitor to Shell in the North Sea, offshore oil and gas production, LNG, and renewable energy. Formerly known as Statoil, the company has expanded beyond its traditional Norwegian upstream operations.
Equinor’s portfolio is strongly concentrated in the Norwegian Continental Shelf, where it is one of the largest producers. Its operations include major fields such as Johan Sverdrup, which is among the largest producing oil fields in Western Europe.
Equinor competes with Shell for offshore exploration licenses, development projects, engineering capabilities, and production opportunities in the North Sea. The two companies also participate in partnerships and shared infrastructure across the region.
Offshore wind has been another important area of competition. Equinor developed Hywind Scotland, the world’s first floating offshore wind farm, and has participated in major offshore wind projects such as Dogger Bank in the United Kingdom.
However, Equinor has adjusted its renewable energy ambitions in response to changing project economics and market conditions. Its current strategy places greater emphasis on profitability, operational performance, and disciplined investment.
Equinor remains a significant competitor to Shell because of its strong offshore expertise, natural gas production, and established position in European energy markets.
11. Petrobras (Petróleo Brasileiro)

Petrobras is Brazil’s state-controlled oil and gas company and one of the world’s most important deepwater oil producers. It competes with Shell in offshore exploration, production, refining, natural gas, and international energy investments.
Petrobras reported sales revenue of approximately $89.2 billion in 2025. Its financial performance is closely linked to crude oil prices, production volumes, refining margins, and exchange-rate movements.
The company’s most important production region is Brazil’s pre-salt offshore basin. These fields have become major sources of oil production because of their scale, reservoir quality, and relatively competitive production economics.
Shell is both a partner and competitor in Brazil’s offshore sector. The companies participate in different exploration and production projects, including joint ventures in the country’s pre-salt region.
Petrobras has a strong domestic position in oil production, refining, and fuel distribution. Its role in Brazil’s energy infrastructure and its relationships with the government provide advantages in the domestic market.
The company has also outlined investments in exploration, biofuels, renewable energy, and other lower-carbon technologies. These initiatives are intended to diversify its portfolio while maintaining oil and gas production as a central source of revenue.
12. CNOOC (China National Offshore Oil Corporation)
CNOOC is one of China’s largest offshore oil and gas producers. It competes with Shell in offshore exploration, natural gas, LNG, international upstream projects, and energy supply to Asian markets.
CNOOC has expanded its production through offshore developments in China and international projects. Its portfolio includes assets in regions such as Guyana, where it holds a participating interest in the Stabroek Block alongside ExxonMobil and other partners.
The Stabroek Block is one of the world’s most significant recent offshore oil discoveries. Its development has created a major production hub in Guyana and strengthened the international positions of the companies involved.
CNOOC’s offshore expertise and access to China’s domestic energy market provide important competitive advantages. Its production growth and investments in new offshore projects have helped it become an increasingly influential international energy company.
The company also competes with Shell for exploration opportunities in offshore regions, particularly where deepwater engineering capabilities and access to capital are important.
CNOOC’s international operations and its position in China’s energy sector make it an important competitor in upstream oil and gas. However, its business model is more concentrated on exploration and production than Shell’s integrated global operations.
13. Repsol
Repsol is a Spanish integrated energy company with operations across upstream production, refining, chemicals, fuel retail, electricity, and renewable energy. It competes with Shell particularly in European and Latin American energy markets.
Repsol reported net income of approximately €1.9 billion in 2025, while adjusted net income reached approximately €2.6 billion. The company’s financial results reflected lower oil prices and challenging market conditions, partly offset by its integrated business portfolio.
Repsol operates a substantial refining network in Spain and has developed businesses in renewable electricity, retail energy, and low-carbon fuels. Its customer-facing operations provide competition for Shell in fuel marketing and energy services.
The company’s renewable power business includes solar and wind projects, while its broader energy strategy also includes hydrogen and renewable fuels. Repsol has continued to revise its investment priorities in response to market conditions and project economics.
Repsol competes with Shell in exploration and production across several international regions, including the North Sea and Latin America. Its refining and fuel retail operations also give it a strong position in Spain.
The company’s combination of conventional energy, refining, and renewable power makes it a relevant competitor to Shell, particularly in European markets.
14. Occidental Petroleum
Occidental Petroleum, commonly known as Oxy, is a US-based energy company that competes with Shell in upstream oil and gas, chemicals, and carbon management. Its operations are concentrated in the United States, the Middle East, and selected international markets.
Occidental reported net sales of approximately $21.6 billion in 2025. The company has a substantial presence in the Permian Basin, where its oil and gas operations benefit from established infrastructure and production expertise.
Its acquisition of CrownRock in 2024 strengthened its Permian portfolio and expanded its position in US shale production. The acquisition added significant acreage and production capacity to its upstream business.
One of Occidental’s most distinctive strategic areas is carbon management. Through its subsidiary 1PointFive, the company is developing Stratos, a large direct air capture facility designed to capture up to 500,000 tonnes of carbon dioxide annually when fully operational.
This investment gives Occidental a prominent position in direct air capture and carbon removal technologies. Shell also invests in carbon capture and storage, but the companies have different project portfolios and commercial approaches.
Occidental’s OxyChem business produces chemicals including chlorine, caustic soda, and vinyl chloride products. These operations compete with parts of Shell’s chemicals portfolio and serve overlapping industrial markets.
15. Valero Energy
Valero Energy is one of the world’s largest independent petroleum refiners. Unlike Shell, it does not operate a comparable global upstream oil and gas production business, but it is a significant competitor in refining, fuel supply, and renewable fuels.
Valero reported revenue of approximately $122.7 billion in 2025. Its business includes petroleum refining, ethanol production, and renewable diesel operations.
The company’s refining network processes crude oil into gasoline, diesel, jet fuel, and other petroleum products. Its refineries are located primarily in the United States, Canada, and the United Kingdom.
Valero’s refining operations compete with Shell’s remaining refining and chemicals facilities for crude oil supplies, product customers, and refining margins. The companies also compete in the supply of transportation fuels to wholesale and commercial customers.
Valero operates Diamond Green Diesel through a joint venture with Darling Ingredients. The business produces renewable diesel and sustainable aviation fuel, making it a significant competitor in lower-carbon transportation fuels.
The company’s focus on refining and renewable fuels makes it a more specialized competitor than Shell. Nevertheless, its scale and ability to process different crude grades give it an important position in global fuel markets.
16. Phillips 66
Phillips 66 is a diversified downstream and midstream energy company. It competes with Shell primarily in refining, chemicals, fuel marketing, transportation, storage, and renewable fuels.
The company was created in 2012 when ConocoPhillips separated its downstream operations. Its business portfolio includes refining, midstream transportation, chemicals through its joint venture with Chevron, and marketing.
Phillips 66 operates a substantial refining network in the United States and Europe. Its facilities process crude oil and other feedstocks into transportation fuels and industrial products.
The company also participates in the chemicals market through Chevron Phillips Chemical, a 50/50 joint venture with Chevron. The joint venture produces petrochemicals and polymers that compete with Shell’s chemicals business.
Phillips 66’s Rodeo Renewed project in California converted its former petroleum refinery into a renewable fuels facility. The project is designed to produce renewable diesel and sustainable aviation fuel, positioning the company in a market where Shell is also developing lower-carbon fuel solutions.
Phillips 66’s midstream operations include pipelines, terminals, and natural gas liquids infrastructure. These assets support energy transportation and storage across North America, while its marketing business competes with Shell in selected fuel distribution markets.
17. Reliance Industries
Reliance Industries is India’s largest private-sector company and one of Asia’s most diversified business groups. It competes with Shell in refining, petrochemicals, natural gas, fuel retail, and emerging clean energy markets.
Reliance reported gross revenue of approximately ₹11.76 trillion ($124 billion) for FY2026, the financial year ended March 31, 2026. Its businesses include Oil-to-Chemicals, retail, digital services, oil and gas, and new energy.
The company’s Jamnagar refining complex in Gujarat is one of the world’s largest refining hubs. Its scale and integration give Reliance a significant competitive position in global refining and petrochemicals markets.
Reliance also operates a major fuel retail business through its partnership with BP, which markets fuel and mobility services under the Jio-bp brand. This creates a direct competitive relationship with Shell’s Indian fuel retail operations.
The company’s Jio digital platform and Reliance Retail network provide extensive access to Indian consumers. These businesses also create opportunities to integrate energy, mobility, digital payments, and retail services.
Reliance has committed substantial investment to its New Energy business, including solar manufacturing, battery storage, hydrogen electrolyzers, and fuel cells. Its plans are intended to build an integrated clean energy manufacturing ecosystem in India.
Reliance’s scale in refining, petrochemicals, retail, and digital services makes it one of Shell’s most important competitors in the Indian market. Its investment in new energy also creates potential competition in technologies and infrastructure that will become increasingly important to the energy sector.
Conclusion
Shell operates in a highly competitive global energy market that includes integrated oil and gas companies, state-owned national energy producers, independent exploration and production businesses, and specialized downstream companies. ExxonMobil, Chevron, BP, and TotalEnergies compete with Shell across several major business segments, while Saudi Aramco, PetroChina, Sinopec, and Petrobras have substantial influence in their respective markets.
Shell’s competitive position is supported by its integrated business model, international LNG portfolio, trading capabilities, upstream production, and global mobility operations. Its 2025 performance included adjusted earnings of $18.5 billion, operating cash flow of $42.9 billion, and LNG sales of 73 million tonnes.
However, competition is not limited to oil and gas production. Companies such as TotalEnergies, Equinor, Eni, Reliance, and Occidental are investing in different parts of the energy transition, including renewable electricity, hydrogen, carbon capture, biofuels, and battery technologies.
Shell’s long-term competitiveness will depend on its ability to maintain strong returns from its core businesses while adapting to changing energy demand, regulation, technology, and customer expectations. Its global scale and integrated portfolio provide important advantages, but competitors continue to challenge its position across individual markets and business segments.
Frequently Asked Questions (FAQs)
1. Who are Shell’s biggest competitors?
Shell’s major global competitors include ExxonMobil, BP, Chevron, TotalEnergies, and Saudi Aramco. These companies compete with Shell across oil and gas production, LNG, refining, chemicals, and international energy markets.
2. Which company is Shell’s closest competitor?
ExxonMobil is one of Shell’s closest overall competitors because both companies operate across upstream production, LNG, refining, chemicals, trading, and fuel marketing. Chevron, BP, and TotalEnergies are also direct competitors across several major business segments.
3. Is ExxonMobil bigger than Shell?
ExxonMobil has a larger upstream production base than Shell. In 2025, ExxonMobil produced approximately 4.7 million barrels of oil equivalent per day, compared with Shell’s approximately 2.8 million barrels per day.
However, company size depends on the measure used. Revenue, market capitalization, production, LNG sales, refining capacity, and profitability provide different perspectives on their relative scale.
4. Who competes with Shell in the LNG market?
Shell competes with companies including TotalEnergies, ExxonMobil, Chevron, BP, QatarEnergy, and other major LNG suppliers. Competition is based on production capacity, long-term supply contracts, shipping, trading capabilities, and access to international customers.
5. Which companies compete with Shell in India?
Reliance Industries, BP through its Jio-bp partnership, Indian Oil Corporation, Bharat Petroleum, and Hindustan Petroleum compete with Shell in India’s fuel retail and energy markets. Reliance also competes in refining, petrochemicals, and emerging clean energy businesses.
6. Does Shell compete with renewable energy companies?
Yes. Shell competes with energy companies and renewable power developers in electricity, offshore wind, solar power, hydrogen, EV charging, and lower-carbon fuels. Relevant competitors include TotalEnergies, Equinor, BP, Eni, and other renewable energy businesses.
7. Is Saudi Aramco a competitor of Shell?
Yes. Saudi Aramco competes with Shell in crude oil production, natural gas, refining, petrochemicals, and international energy supply. Its large reserves, low-cost production base, and state ownership give it a different competitive structure from Shell.
8. What gives Shell a competitive advantage?
Shell’s competitive advantages include its global LNG portfolio, integrated energy operations, trading capabilities, international customer relationships, upstream assets, and mobility network. These capabilities allow the company to participate in several stages of the energy value chain.
9. Which companies compete with Shell in refining and chemicals?
ExxonMobil, Chevron, TotalEnergies, PetroChina, Sinopec, Reliance Industries, Valero, and Phillips 66 compete with Shell in different parts of refining and chemicals. Their competitive overlap depends on geography, product categories, feedstock, and customer markets.
10. Is Shell larger than BP?
Shell and BP are both major European integrated energy companies, but Shell has a larger production and LNG business. In 2025, Shell’s production was approximately 2.8 million barrels of oil equivalent per day, compared with BP’s approximately 2.3 million barrels per day.
Their relative size can differ depending on whether the comparison uses revenue, earnings, production, market capitalization, or specific business segments.
Also Read: Palantir Competitors: 17 AI & Data Analytics Rivals Ranked
To read more content like this, subscribe to our newsletter