Last Updated on September 22, 2026 by Team TBH
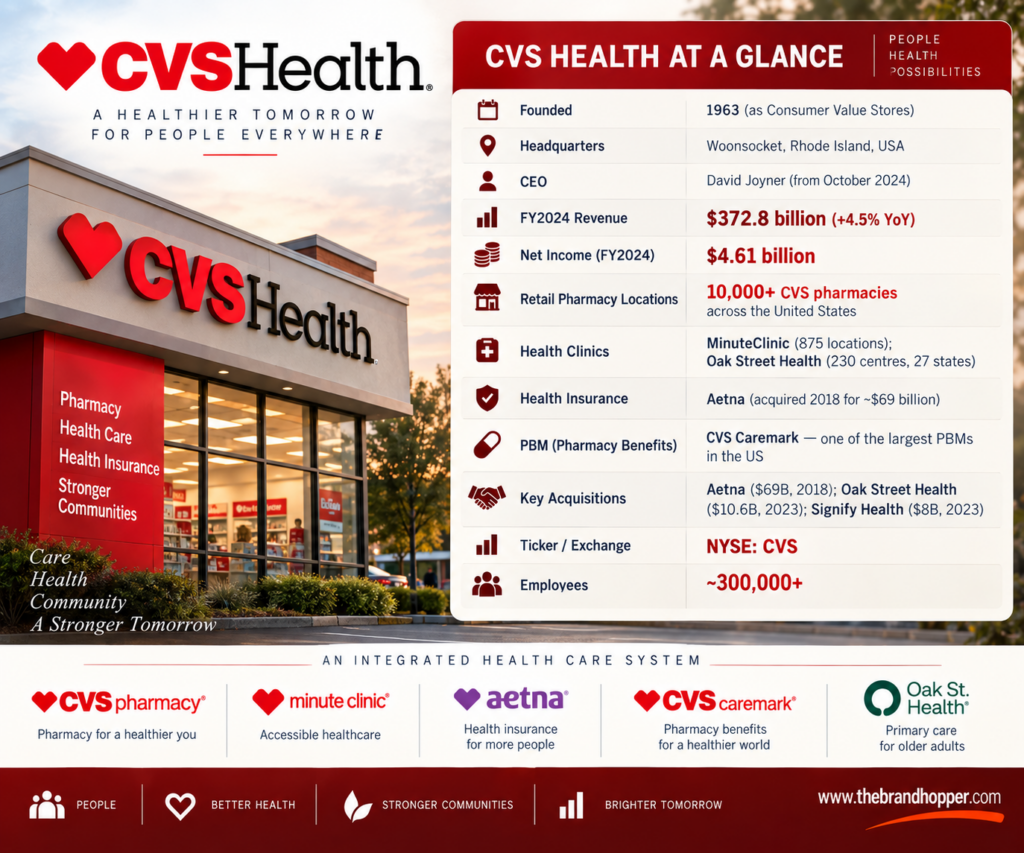
The pharmacy and healthcare services industry is one of the most dynamic, capital-intensive, and rapidly evolving sectors in the global economy. CVS Health — with $372.8 billion in revenue for the full year 2024 — is one of the largest healthcare companies in the world, blending retail pharmacy, pharmacy benefit management (PBM), health insurance through Aetna, and primary care through Oak Street Health.
Yet despite its scale, CVS operates in an environment where the rules are being rewritten. The global pharmacy retail market is projected to exceed $1.5 trillion, and competition is arriving from every direction: traditional pharmacy chains, health insurance titans with integrated PBMs, technology-first digital pharmacies, direct-to-consumer telehealth platforms, and price-disrupting startups like Mark Cuban’s Cost Plus Drugs.
This article identifies and analyses 16 of the most significant competitors challenging CVS Health across its various business segments — retail pharmacy, PBM, health insurance, primary care clinics, and digital health.
This is not a static market. Rite Aid — once America’s third-largest pharmacy chain — has permanently closed all its stores following a second bankruptcy filing in 2025. Walgreens Boots Alliance is being taken private by Sycamore Partners, exiting the public markets entirely. Walmart shuttered all 51 of its Walmart Health clinics in 2024. These seismic shifts have changed the competitive map for CVS Health and opened opportunities for both incumbents and digital-first challengers alike.
The Evolving Landscape of Pharmacy and Healthcare Services
The pharmacy and healthcare ecosystem that CVS Health navigates today looks fundamentally different from even five years ago. Three interconnected forces are reshaping the competitive environment:
Integration and vertical consolidation: Health insurers are acquiring PBMs, PBMs are opening pharmacies, and pharmacies are building primary care networks. UnitedHealth Group’s Optum division, Cigna’s Evernorth, and Elevance Health’s CarelonRx all represent this trend — healthcare conglomerates assembling vertically integrated stacks that can control the full patient journey from insurance to prescription to care delivery.
Digital disruption: Amazon Pharmacy, Hims & Hers Health, and Capsule have demonstrated that consumers will embrace alternative pharmacy models when they offer greater convenience, price transparency, or ease of access. The GLP-1 (semaglutide/Ozempic) weight-loss drug boom has turbocharged telehealth pharmacies, with Hims & Hers projecting $725 million in weight-loss revenues alone for 2025 — a business that barely existed in 2023.
Price transparency and disruption: Mark Cuban’s Cost Plus Drugs and GoodRx have exposed the opacity in drug pricing, accelerating consumer willingness to step outside traditional PBM networks. The PBM industry itself faces intense congressional and regulatory scrutiny, with FTC investigations into pharmacy benefit managers threatening the profitability models of CVS Caremark, OptumRx, and Express Scripts.
Against this backdrop, CVS Health under CEO David Joyner (who replaced Karen Lynch in October 2024) is executing a $2 billion cost-reduction programme, rationalising its MinuteClinic footprint from 1,150 locations in 2023 to 875 by end of 2024, and refocusing Aetna away from unprofitable Medicare Advantage markets. The company’s strategic identity — healthcare company or pharmacy chain? — remains contested. And that ambiguity creates openings for every competitor on this list.
Top 17 Competitors of CVS Health
1. Walgreens Boots Alliance
Website: walgreensbootsalliance.com
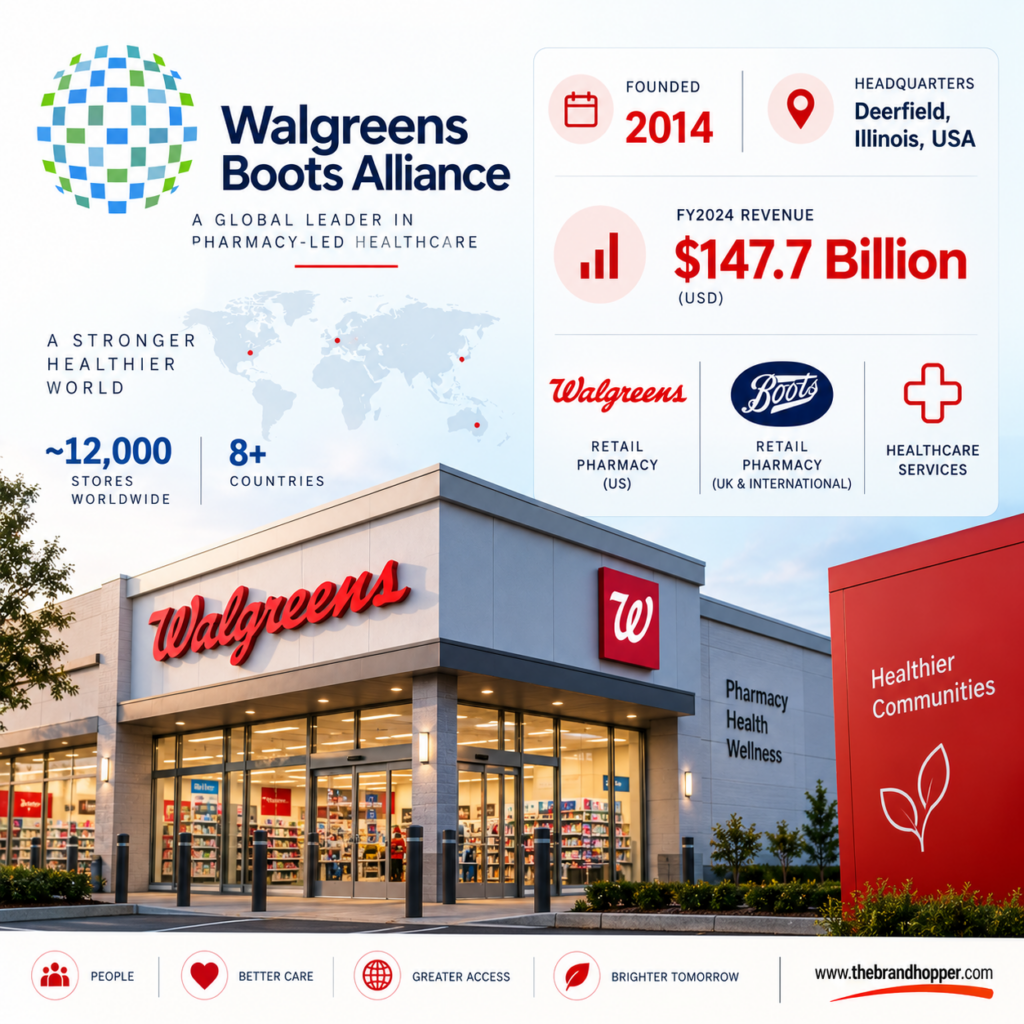
If CVS Health has a single most direct rival, it remains Walgreens Boots Alliance — the company that shares a similar store footprint, similar product mix, and similar ambitions in health services. Yet Walgreens is undergoing a transformation more dramatic than its American competitor: in June 2025, Sycamore Partners agreed to take the company private in a deal valuing Walgreens at approximately $10 billion, ending its nearly 100-year run as a public company.
For its fiscal third quarter ending May 31, 2025, Walgreens reported US and global pharmacy sales of $39.0 billion, up 7.2% from the prior-year quarter. Its US retail pharmacy segment remains its largest business, operating approximately 8,500 stores after a sustained programme of closures that reduced its footprint from over 9,000 locations. In 2024, Walgreens wound down its VillageMD primary care partnership, which had seen 220+ full-service doctor offices co-located in Walgreens stores — a direct retreat from the strategy that most threatened CVS’s MinuteClinic model.
The contrast with CVS is instructive. Where CVS has doubled down on the health services narrative — despite its own operational challenges — Walgreens has retreated from primary care and refocused on core pharmacy and consumer health retail. Under new ownership, Walgreens’s private-company structure will give it greater flexibility to restructure without quarterly earnings pressure. The underlying pharmacy footprint and brand loyalty remain substantial competitive assets for CVS to respect.
2. Amazon Pharmacy
Website: pharmacy.amazon.com
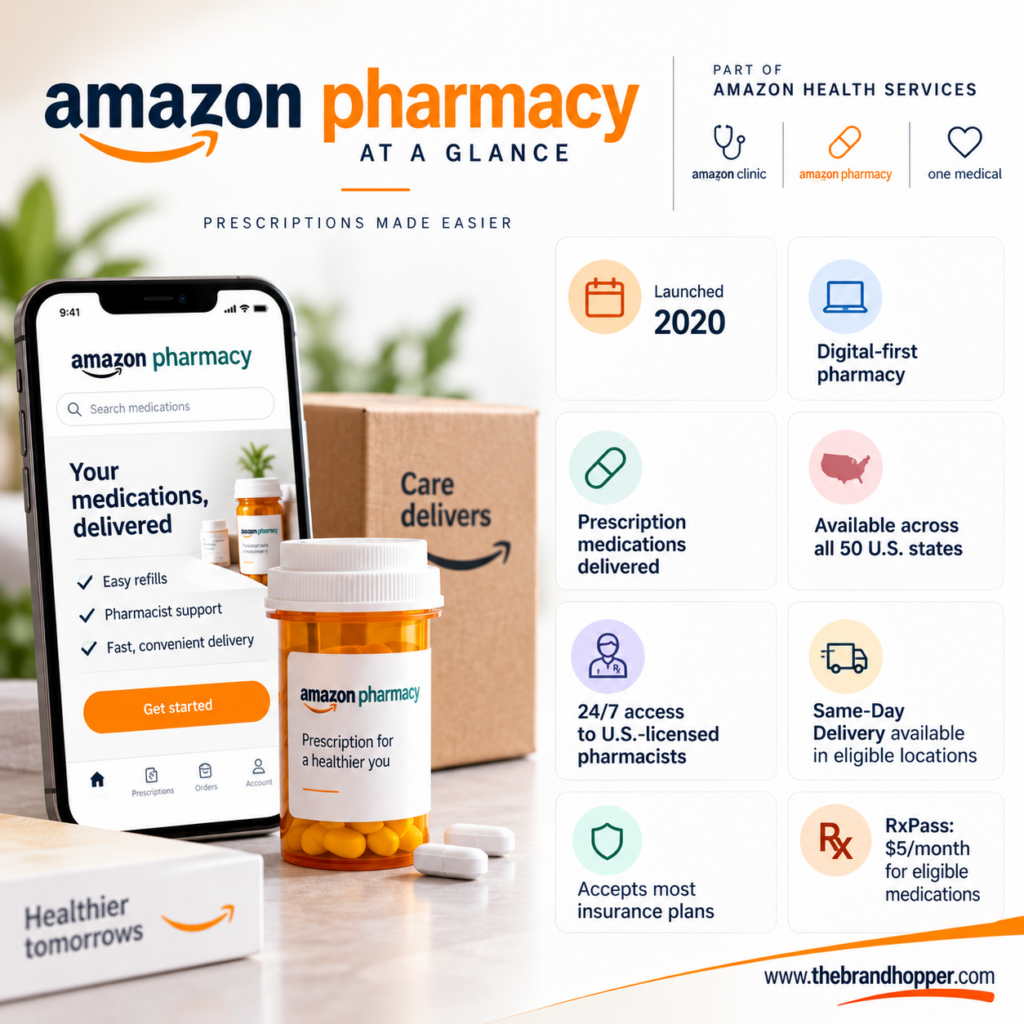
When Amazon acquired PillPack for $1 billion in 2018 and relaunched it as Amazon Pharmacy in 2020, many dismissed the threat. Those doubters are increasingly quiet. Amazon Pharmacy is estimated to have generated between $1.25 billion and $2 billion in prescription revenues in 2024, with projections for continued rapid growth as same-day delivery expands.
The company announced plans to open pharmacies in 20 new cities in 2025, targeting a position where 45% of US consumers can access free same-day prescription delivery by end of 2025. RxPass — Amazon’s $5 per month subscription offering access to 60 generic medications for Prime members — has demonstrated measurable clinical impact: a published study found RxPass subscribers saw a 27% increase in days’ supply and a 30% decrease in out-of-pocket costs. As of late 2024, approximately 13% of US adults reported having used Amazon Pharmacy in the past 12 months.
Amazon’s competitive advantages are structural: its Prime membership base of over 200 million subscribers provides a built-in patient acquisition channel; its logistics network enables delivery speeds CVS’s own delivery programme cannot match; and its customer experience and data infrastructure give it meaningful advantages in convenience, medication adherence, and personalisation. CVS’s response — expanding its own prescription delivery options and CarePass membership — has been credible but lagged the e-commerce giant’s pace.
3. UnitedHealth Group (OptumRx)
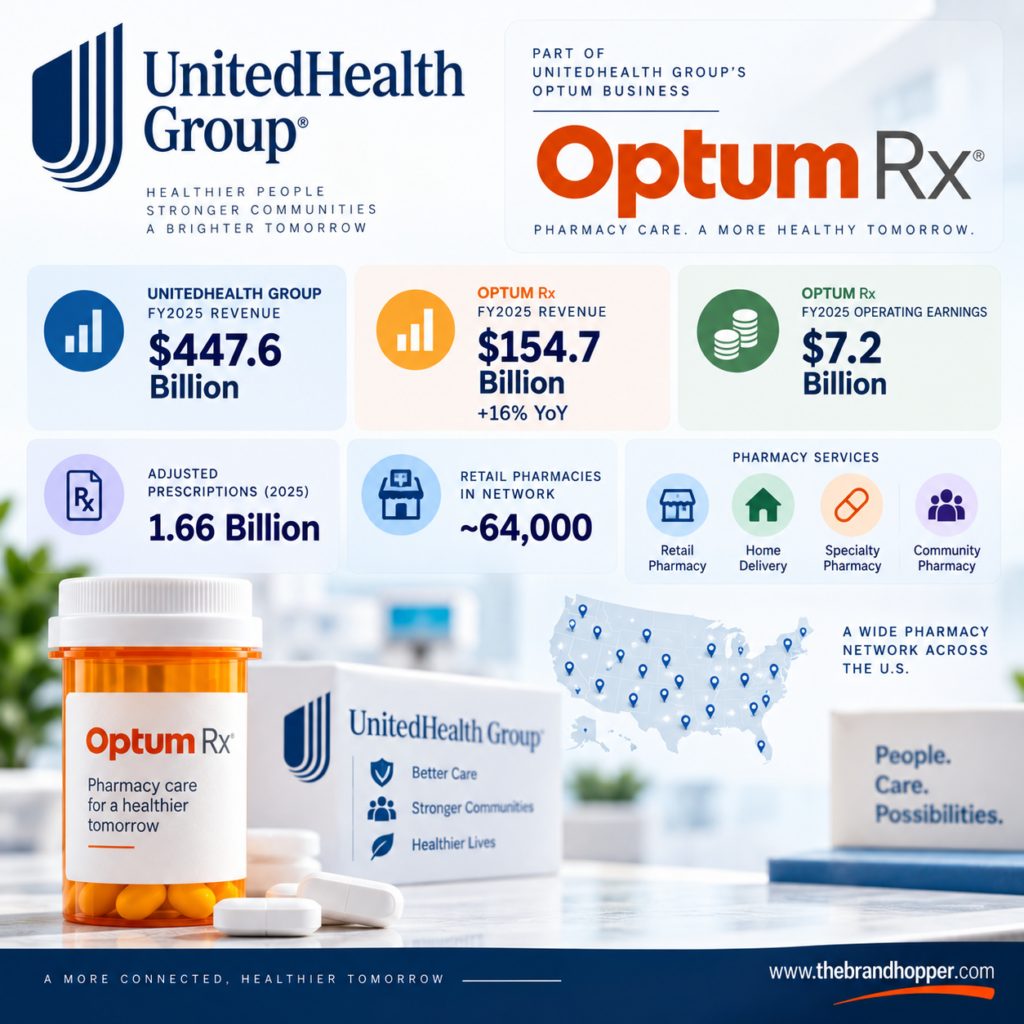
Website: unitedhealthgroup.com
UnitedHealth Group is, by revenue, one of the largest corporations in the United States. The company reported $400.3 billion in total revenues for the full year 2024, up 6% year-over-year — a scale that dwarfs even CVS Health’s $372.8 billion. Its Optum division — which encompasses OptumRx (PBM), Optum Health (care delivery), and OptumInsight (data and analytics) — generated $253 billion in revenue in 2024, up 12% year-over-year.
OptumRx is the most significant competitive threat to CVS’s Caremark PBM business. OptumRx processed 1.62 billion adjusted scripts in 2024, up from 1.54 billion in 2023, with revenues growing 15% driven by new client wins and expanded existing client relationships. The integration of OptumRx with UnitedHealthcare’s insurance products — which generated $298.2 billion in revenue in 2024 — creates data synergies and care coordination capabilities that a standalone PBM like Caremark cannot easily replicate.
The broader UnitedHealth / Optum strategy mirrors CVS’s: vertically integrating across insurance, pharmacy, and care delivery. UnitedHealth owns nearly 90,000 physicians and clinicians through Optum Health, giving it primary care capabilities that compete directly with Oak Street Health. This integrated model — combining payer, PBM, and provider — represents the direction the entire industry is moving, and the company doing it at the largest scale is UnitedHealth.
4. Kroger Health
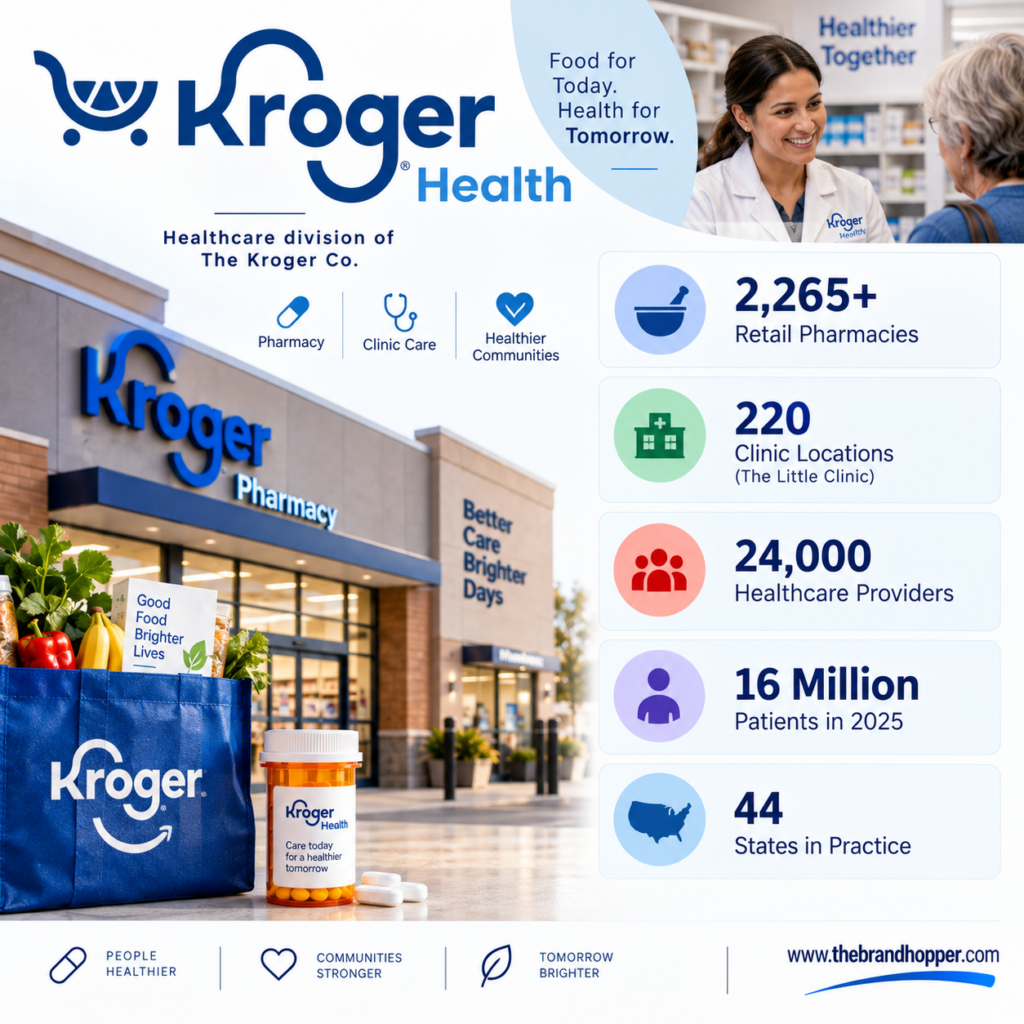
Website: krogerhealth.com
Kroger Health operates one of the largest pharmacy networks embedded within a grocery chain, with approximately 2,200 in-store pharmacies and more than 220 Little Clinics across 35 US states. In 2024, Kroger made a significant strategic pivot: it sold its Kroger Specialty Pharmacy business to Elevance Health’s CarelonRx arm for $464 million, completed in October 2024. While this exit from specialty pharmacy may appear to be a retreat, Kroger framed it as an asset optimisation — focusing on its strengths in in-store retail pharmacy and nutrition-based health services rather than the highly complex specialty drug management business.
Kroger’s competitive advantage against CVS is its grocery integration: the company leverages its vast food and nutrition expertise to offer services like telenutrition counselling, diet planning integrated with medication management, and health screenings tied to grocery purchasing data. The model creates a differentiated pharmacy experience — one where filling a prescription for a diabetes medication can be paired with dietary guidance — that CVS’s standalone pharmacy and MinuteClinic format does not replicate.
Kroger’s proposed merger with Albertsons, which would have created a grocery behemoth with over 4,500 locations, was blocked by US federal courts in 2024 on antitrust grounds. The company continues as a major standalone grocery and pharmacy operator, with its health services remaining a formidable competitor to CVS in markets where Kroger and CVS locations overlap.
5. Cigna Group (Evernorth / Express Scripts)
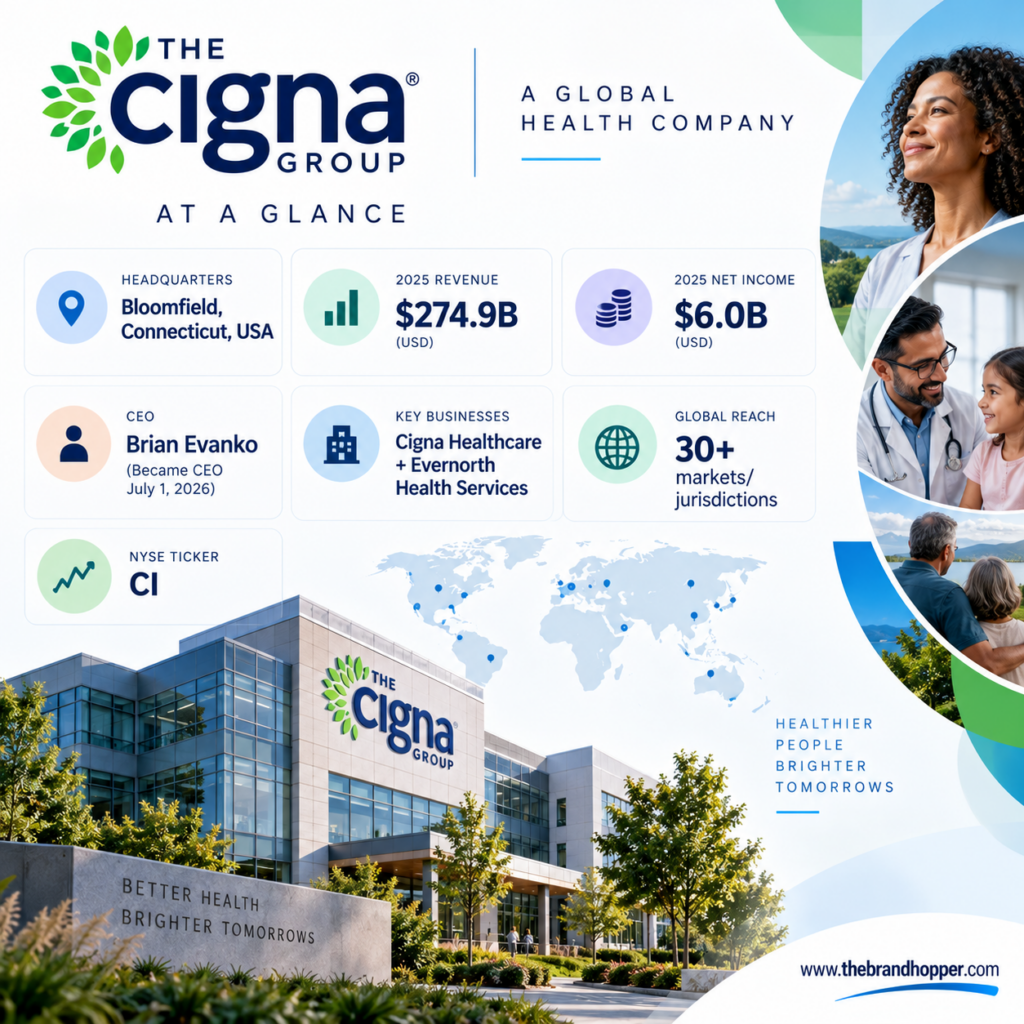
Website: cigna.com
The Cigna Group — operating its health services through the Evernorth Health Services division and its Express Scripts PBM — is CVS Health’s most direct competitor in the pharmacy benefit management space. The company reported $247.1 billion in total revenues for 2024, a 27% year-over-year increase that reflects the dramatic transformation of Express Scripts under the Evernorth umbrella.
Express Scripts was the standout performer in the Cigna portfolio for 2024, growing revenue by 46% — from $76 billion in 2023 to over $111 billion in 2024 — driven by the conversion of the Centene pharmacy book of business and strong commercial client retention. Total pharmacy customers across Evernorth grew 20% to 118.3 million by year-end 2024. The specialty and care services segment added $90.3 billion in adjusted revenue, an 18% increase.
Like CVS’s Caremark, Express Scripts manages prescription drug benefits for employers, health plans, and government programmes. Unlike CVS, Cigna does not operate a retail pharmacy network — meaning it relies entirely on relationships with retail pharmacies (including CVS) and its own mail-order and specialty pharmacy operations. This creates a complex dynamic in which CVS and Cigna are simultaneously competitors and business partners in the PBM ecosystem.
6. Costco Pharmacy
Website: costco.com
Costco’s pharmacy business benefits from one of the most distinctive retail models in the world: a membership-based warehouse club where high volume and low margins create exceptional pricing for members. Costco Wholesale Corporation reported net sales of $237.7 billion for its fiscal year 2024 (ended September 2024), and its pharmacy services — operating across approximately 875 US pharmacy locations within Costco warehouses — are among the most price-competitive in the country.
Costco’s pharmacy competes with CVS most directly on price, particularly for generic medications. Costco’s low-overhead, high-volume operating model allows it to offer generic drug prices that regularly undercut traditional pharmacy chains by a significant margin. For a consumer who already shops at Costco, filling prescriptions there requires minimal additional effort and delivers material savings.
Costco’s limitations as a CVS competitor are its physical footprint (875 locations versus CVS’s 10,000+), its membership requirement (meaning non-members cannot easily access its pharmacy), and its absence from the clinical health services market. Costco does not operate in-store clinics, mental health services, or insurance products. It is a pure pharmacy retail competitor — but on pricing alone, it consistently wins.
7. Capsule
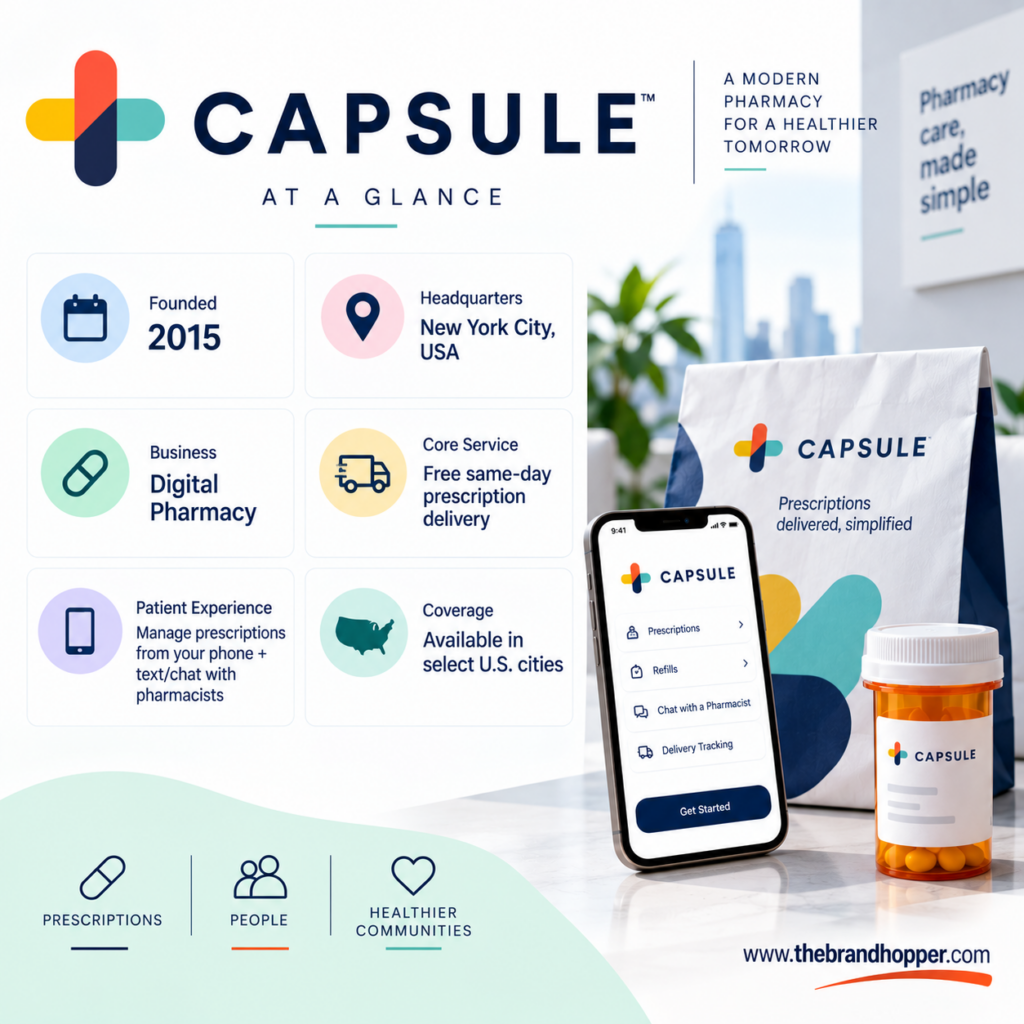
Website: capsule.com
Capsule was founded in 2016 with a mission to make prescription pharmacy as seamless as ordering a rideshare: same-day delivery, technology-first customer experience, automatic refills, and proactive insurance management. The company built a passionate user base — particularly among urban millennials — by eliminating the friction points that make traditional pharmacy visits frustrating.
In 2022, Capsule was acquired by Health Mart Systems, a subsidiary of McKesson Corporation, one of the largest pharmaceutical distribution companies in the world. This acquisition brought Capsule’s technology and consumer experience model into the orbit of a distribution giant with relationships across thousands of independent pharmacies and the infrastructure to scale digital pharmacy capabilities nationally. Following the acquisition, Capsule has continued to operate its consumer-facing brand while benefiting from McKesson’s supply chain scale and negotiating leverage.
For CVS, Capsule represents the leading edge of a consumer expectation shift: patients — especially those under 45 — increasingly expect pharmacy to be as convenient as any other e-commerce experience. The fact that Capsule was acquired and scaled by McKesson rather than collapsing as a standalone startup suggests that the digital pharmacy model has proven viable enough to attract serious institutional investment. CVS’s own app and delivery programmes are a direct response to this competitive pressure.
8. GoodRx
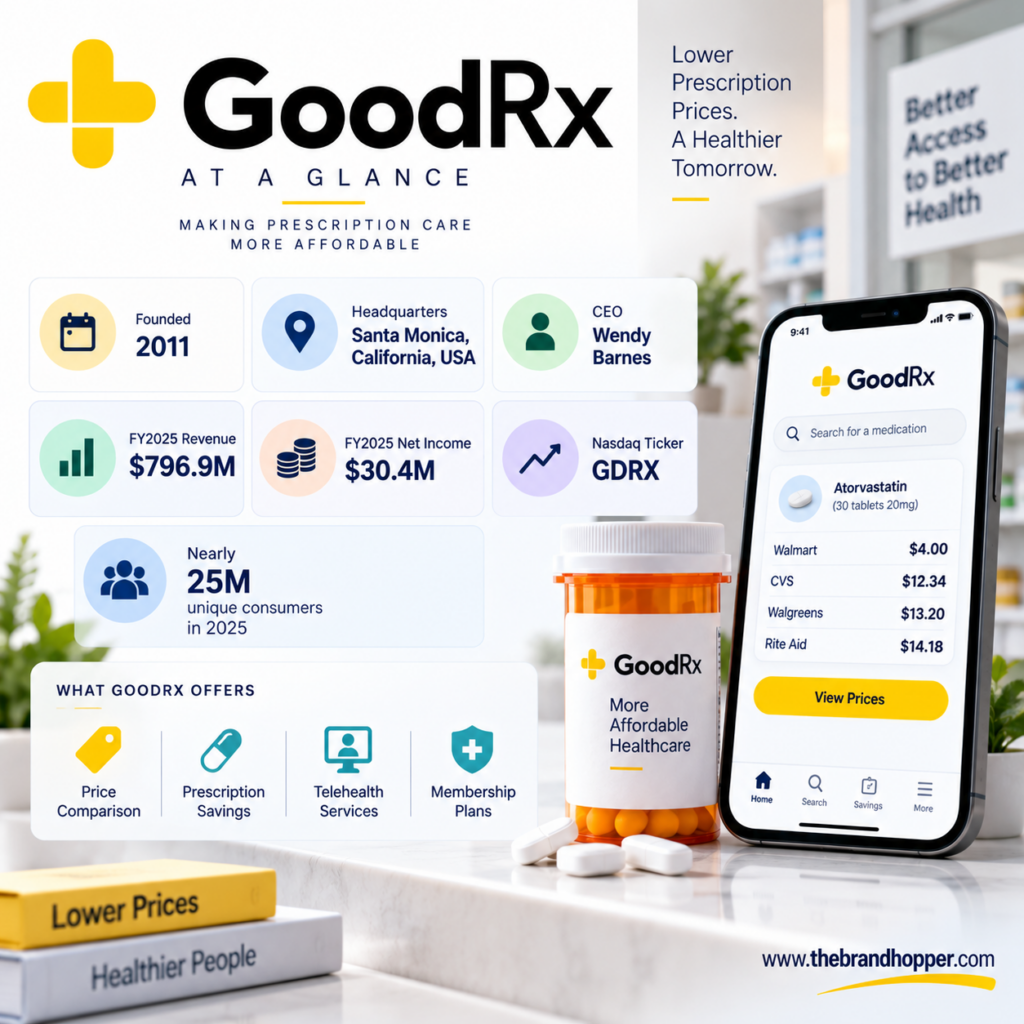
Website: goodrx.com
GoodRx is not a pharmacy — but its impact on the pharmacy industry, including CVS Health, has been profound. By providing consumers with free price comparison tools and negotiated discount coupons for prescription medications at retail pharmacies, GoodRx has introduced a level of pricing transparency that the pharmacy industry had long resisted. Consumers who use GoodRx consistently find prices below what they would pay using their insurance at CVS, Walgreens, or any other major chain.
For the full year 2024, GoodRx reported prescription transactions revenue of $577.5 million (up 5% year-over-year), pharma manufacturer solutions revenue of $107.2 million (up 26%), and subscription revenue of $86.5 million, bringing total revenues to approximately $771 million. The company had over 7 million monthly active prescription consumers as of end-2024, and reported net income of $16.4 million — its first full-year profit after years of losses.
The relationship between GoodRx and CVS is nuanced. CVS participates in GoodRx’s discount programme, accepting GoodRx coupons at CVS pharmacies. In this sense, GoodRx sends customers to CVS. But it simultaneously trains consumers to search for the lowest price rather than developing loyalty to any particular pharmacy chain — a pattern that ultimately erodes the pricing power that CVS depends on. GoodRx’s growing telehealth offering (GoodRx Care) adds another dimension of competitive overlap.
9. Walmart Pharmacy
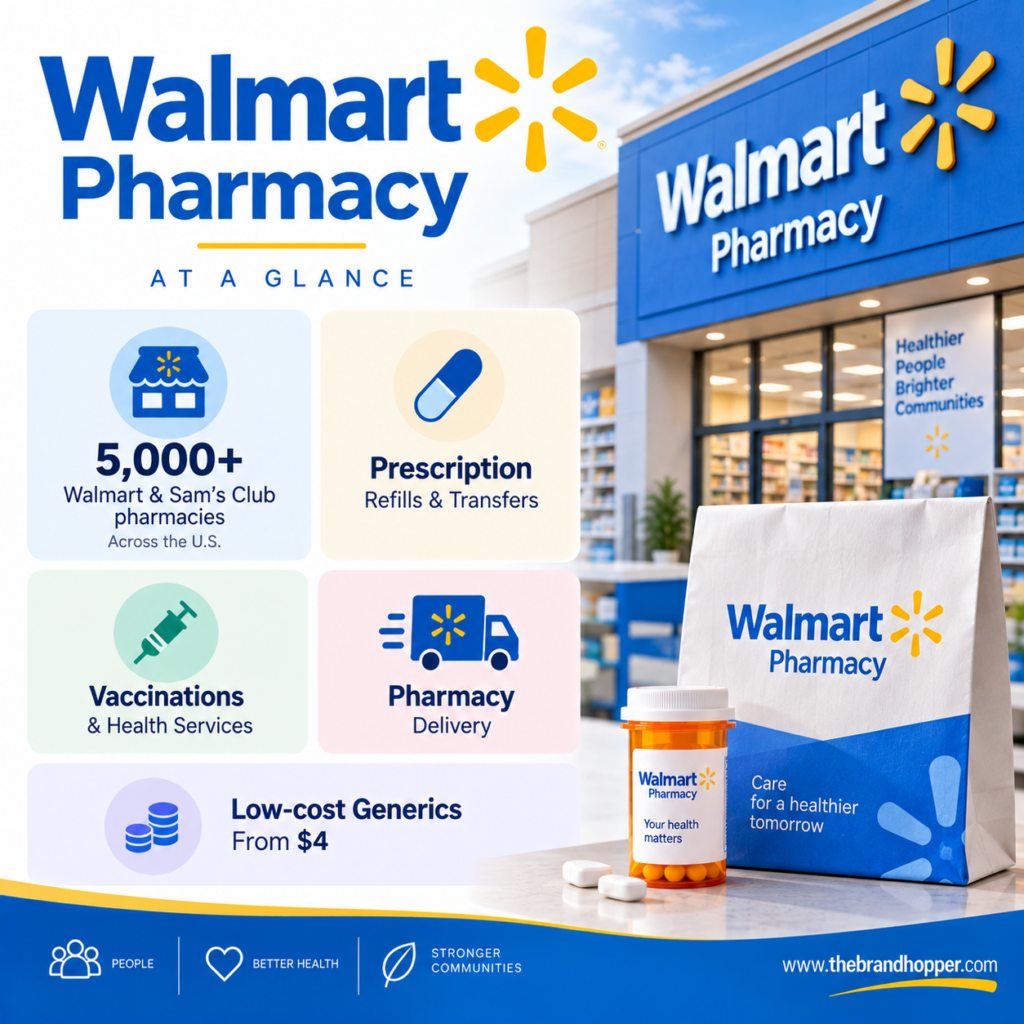
Website: https://www.walmart.com/
Walmart is not primarily a healthcare company, but its pharmacy operations represent one of the largest and most price-competitive pharmacy networks in the United States. Walmart operates approximately 4,600 in-store pharmacies alongside 3,000+ vision centres — a footprint that, while smaller than CVS’s 10,000+ locations, is anchored by the world’s largest retailer with $648 billion in annual revenues (FY2025, ended January 2025).
Walmart Health — its ambitious in-store clinic initiative that aimed to provide affordable primary care — was shut down in April 2024 after operating 51 centres. The company cited an unsustainable reimbursement environment and escalating operating costs as the reasons for closure. The failure of Walmart Health was a significant moment for the industry, reinforcing the difficulty of combining retail and primary care at scale in a market shaped by complex insurance reimbursement structures.
Despite the clinic closures, Walmart’s pharmacy business remains significant. The company’s $4 generic drug programme and $10 90-day supply pricing have long exerted downward pressure on pharmacy pricing across the market. Walmart pharmacies fill tens of millions of prescriptions annually, and the company’s supply chain and purchasing scale give it drug cost advantages comparable to or exceeding those of CVS Caremark in certain generic categories. For uninsured and price-sensitive consumers, Walmart remains one of the most accessible and affordable pharmacy options in the country.
10. Humana (CenterWell)
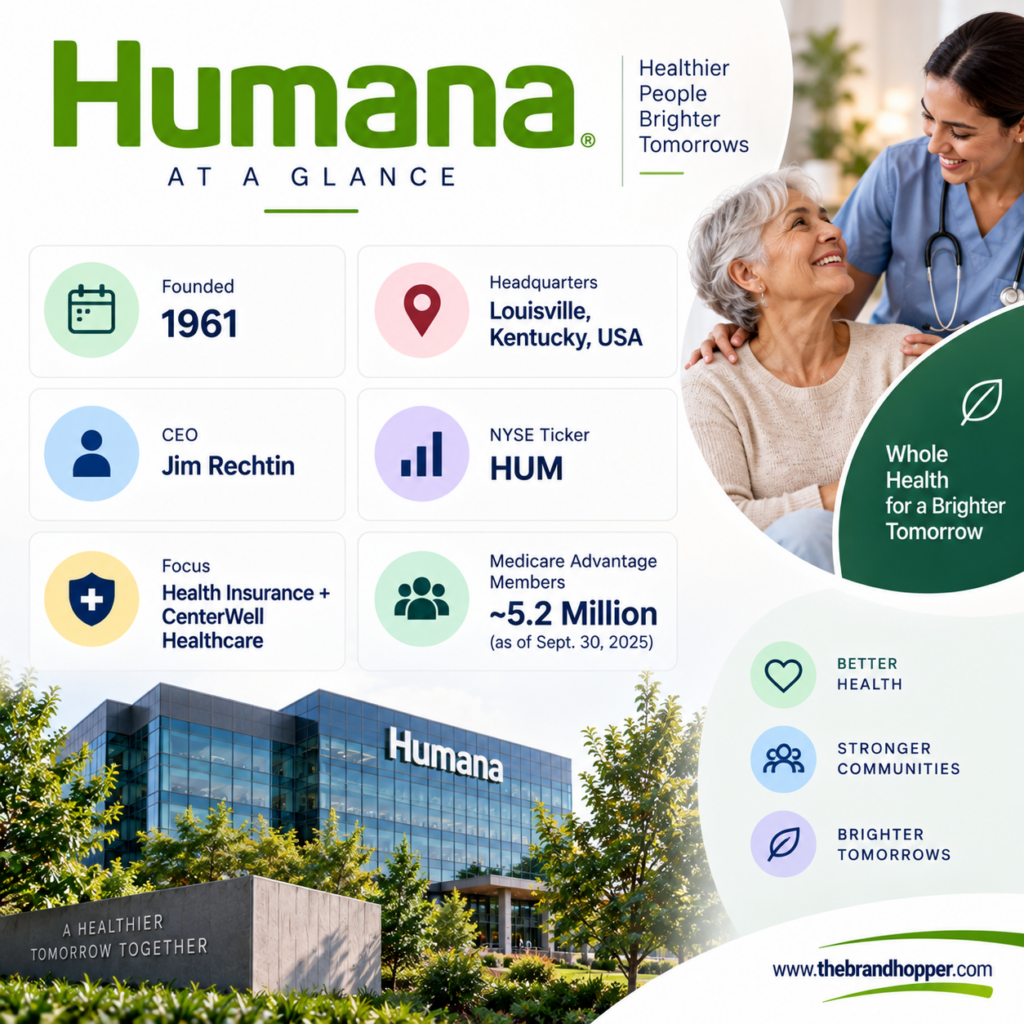
Website: https://www.humana.com/pharmacy
Humana is the second-largest Medicare Advantage insurer in the United States and a significant competitor to CVS’s Aetna division in the senior healthcare market. The company reported consolidated premiums revenue of $112.1 billion in 2024, up 10.7% from $101.3 billion in 2023, reflecting its dominant position in government-sponsored health plans serving seniors.
Humana’s CenterWell brand encompasses its pharmacy operations (CenterWell Pharmacy, which includes mail-order and specialty pharmacy services), its home health division (CenterWell Home Health), and its primary care clinics (CenterWell Senior Primary Care). This integrated model — insurance, pharmacy, home health, and primary care for Medicare-age patients — mirrors CVS’s Aetna + Oak Street Health + Caremark + MinuteClinic model almost exactly, and focuses it on the same high-value, high-cost Medicare population.
Humana and CVS’s Aetna are in direct competition for Medicare Advantage members across most of the United States. The Medicare Advantage market has faced elevated medical cost pressures and unfavourable star ratings adjustments in recent years, affecting both companies. Humana’s scale in Medicare Advantage (approximately 5.2 million MA members), its CenterWell pharmacy assets, and its integrated care model make it one of the most structurally similar competitors to CVS in the health services sector.
11. Elevance Health (CarelonRx)
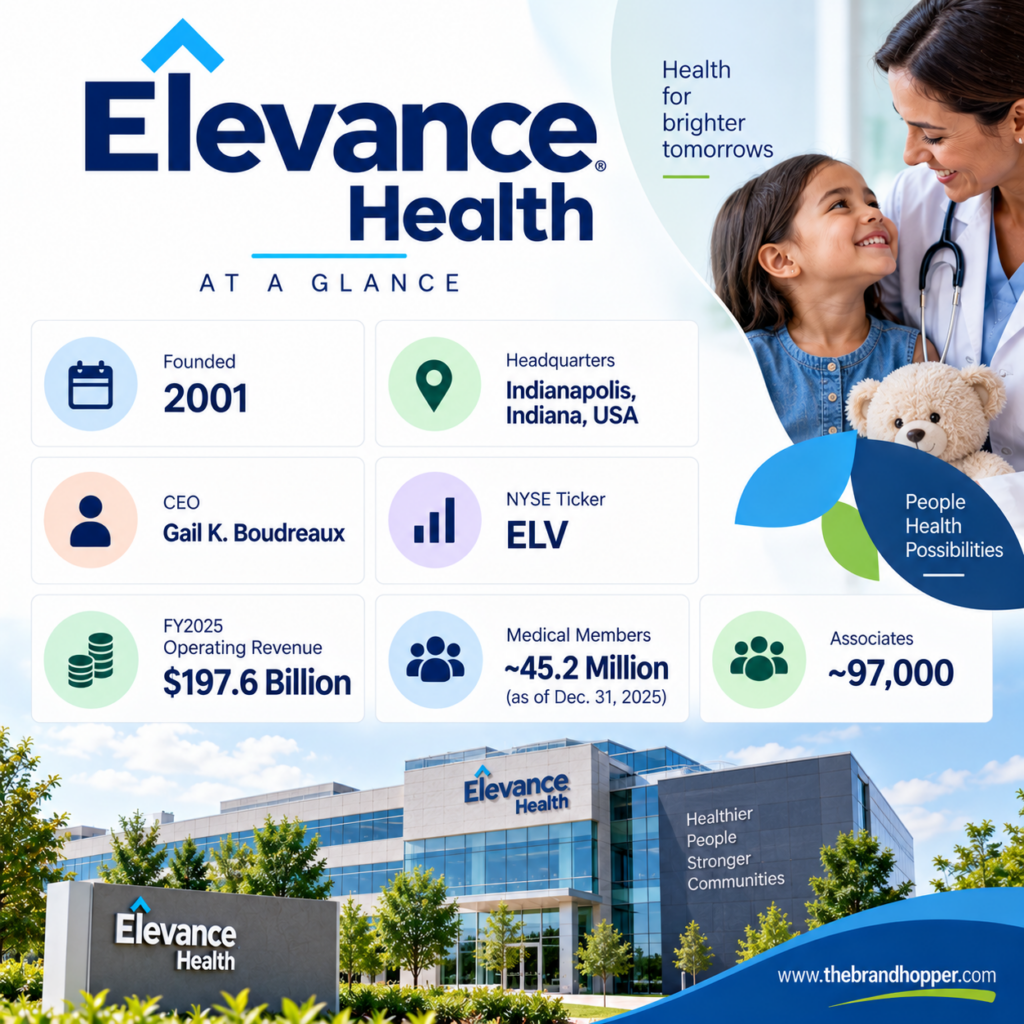
Website: https://www.elevancehealth.com/
Elevance Health — formerly known as Anthem and the parent of the largest Blue Cross Blue Shield plan network — competes with CVS through its CarelonRx pharmacy benefit management platform (formerly IngenioRx). CarelonRx reported revenues of $33.8 billion in its most recent reported period (up 19% year-over-year) and processed 318.4 million adjusted prescription claims, up 3.2% year-over-year.
In October 2024, CarelonRx completed a significant acquisition: the $464 million purchase of Kroger Specialty Pharmacy, one of the largest specialty pharmacy businesses in the US. This acquisition expanded CarelonRx’s capabilities in specialty drug management — a fast-growing segment driven by high-cost biological and oncology therapies — and gives Elevance in-house dispensing capabilities that reduce its dependence on CVS Specialty and other third-party specialty pharmacies.
The relationship between Elevance Health and CVS is particularly layered. CVS Health has provided PBM administrative services to CarelonRx (now called CarelonRx) since 2019, an agreement extended through 2027. This makes them simultaneously competitors in PBM services and business partners in administrative functions. As Elevance builds out its own dispensing capabilities through the Kroger Specialty Pharmacy acquisition, the financial case for renewing the CVS administrative services agreement beyond 2027 becomes increasingly uncertain.
12. Mark Cuban Cost Plus Drugs Company
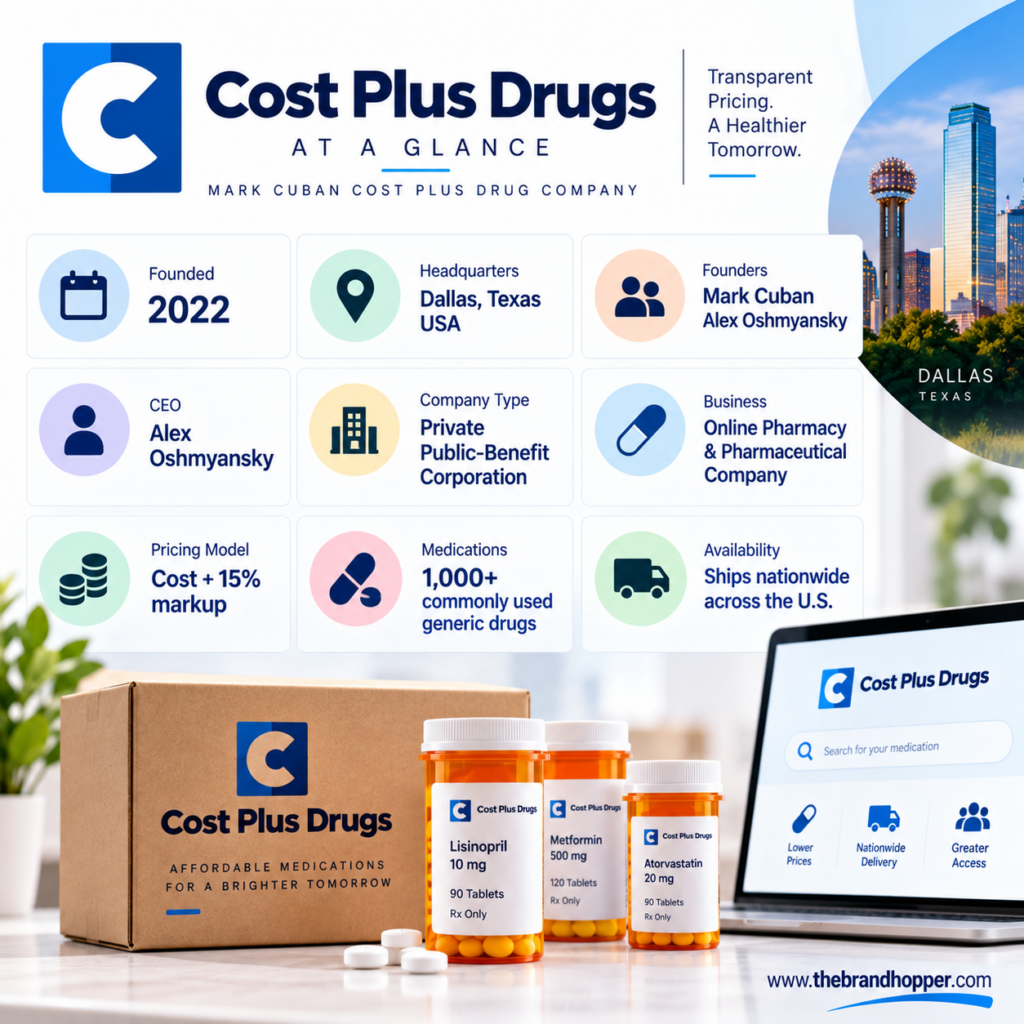
Website: https://www.costplusdrugs.com
Cost Plus Drugs is perhaps the most disruptive new entrant in pharmacy in a decade. Founded by entrepreneur Mark Cuban and physician Alex Oshmyansky in 2022, the company operates on a radically simple pricing model: manufacturing cost + 15% mark-up + $3 pharmacy fee + $5 shipping. No PBM contracts, no rebate games, no opaque reimbursement arrangements — just transparent pricing.
By 2024, Cost Plus Drugs had grown to offer approximately 4,000 medications including generics, branded drugs, and biosimilars, and was estimated to have generated over $100 million in annual revenues. The company opened an $11 million, 22,000-square-foot manufacturing facility in Dallas that began producing generic sterile injectables in 2024, starting with epinephrine and norepinephrine in short supply nationally. The facility can produce millions of doses annually and has since expanded into other medications including paediatric cancer drugs.
Cost Plus Drugs’ competitive threat to CVS is structural, not transactional. By exposing the gap between manufacturer prices and retail pharmacy prices, the company has accelerated public and political pressure on PBMs — including CVS Caremark — to adopt pass-through pricing models that eliminate hidden rebate revenue. Congress has repeatedly considered legislation targeting PBM practices that have long been a profit engine for CVS. The FTC has launched formal investigations into PBM pricing. Cost Plus Drugs sits at the centre of this pressure campaign.
13. Hims & Hers Health
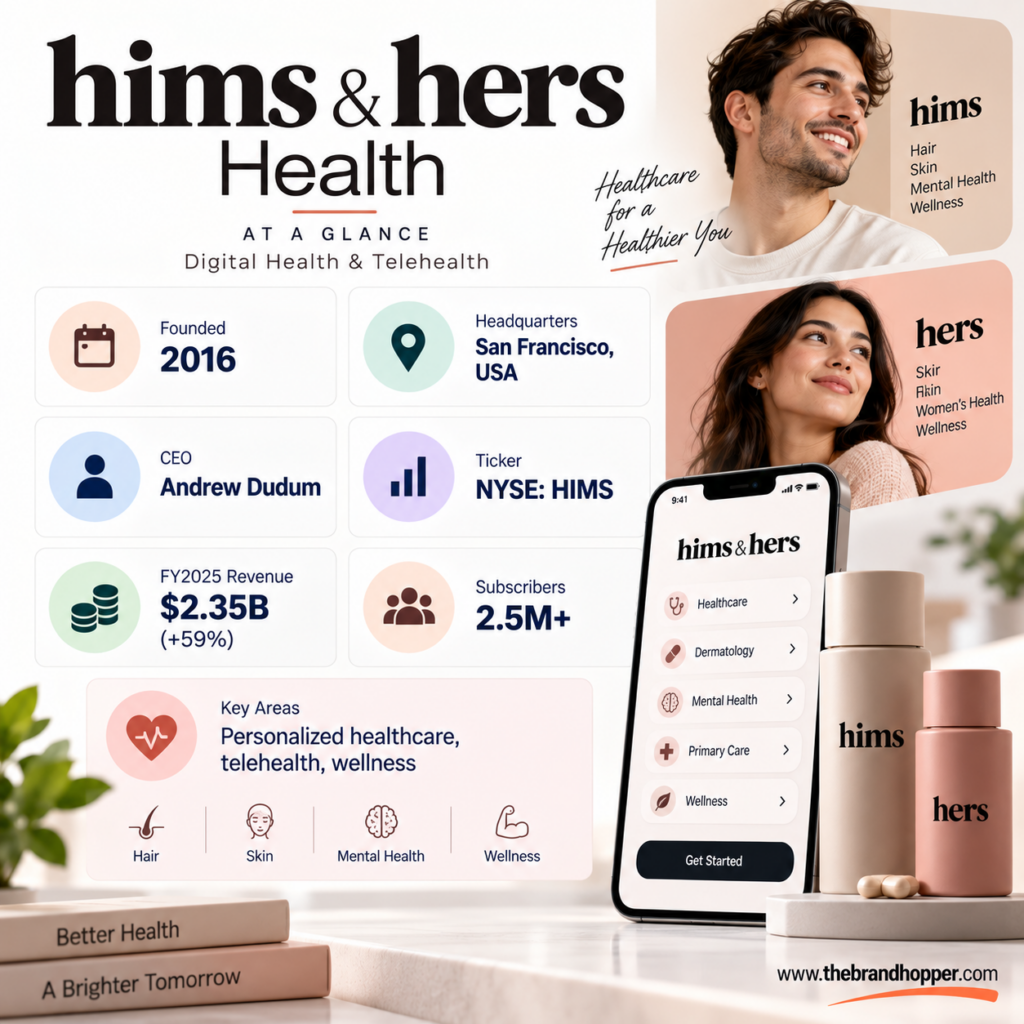
Website: https://www.hims.com/
Hims & Hers Health is the fastest-growing pharmacy and telehealth competitor to emerge in recent years, powered by the GLP-1 weight-loss drug phenomenon. The company reported full-year 2024 revenues of $1.48 billion, up 69% year-over-year from $872 million in 2023, making it one of the fastest-growing health companies in the US. A published revenue target for its weight-loss business alone of $725 million for 2025 underscores the pace of growth.
Hims & Hers combines telehealth consultations with a licensed pharmacy that ships directly to consumers. The company offers treatments across dermatology, sexual health, mental health, hair loss, and weight management — using the same frictionless subscription model that has proven successful in direct-to-consumer e-commerce. Its entry into compounded semaglutide (GLP-1 weight-loss injections) in May 2024, at starting prices of $199 per month versus $1,000+ for branded alternatives, created immediate consumer demand and revenue acceleration.
Hims & Hers competes with CVS at the intersection of clinical services and pharmacy. Where CVS’s MinuteClinic offers in-person care and CVS Caremark manages prescription benefits through employer contracts, Hims & Hers offers a direct-to-consumer model that bypasses insurance entirely — pricing medications at rates accessible without insurance for many common treatments. This positions it as both a competitor and a complementary channel, depending on the patient’s situation and treatment type.
14. Teladoc Health
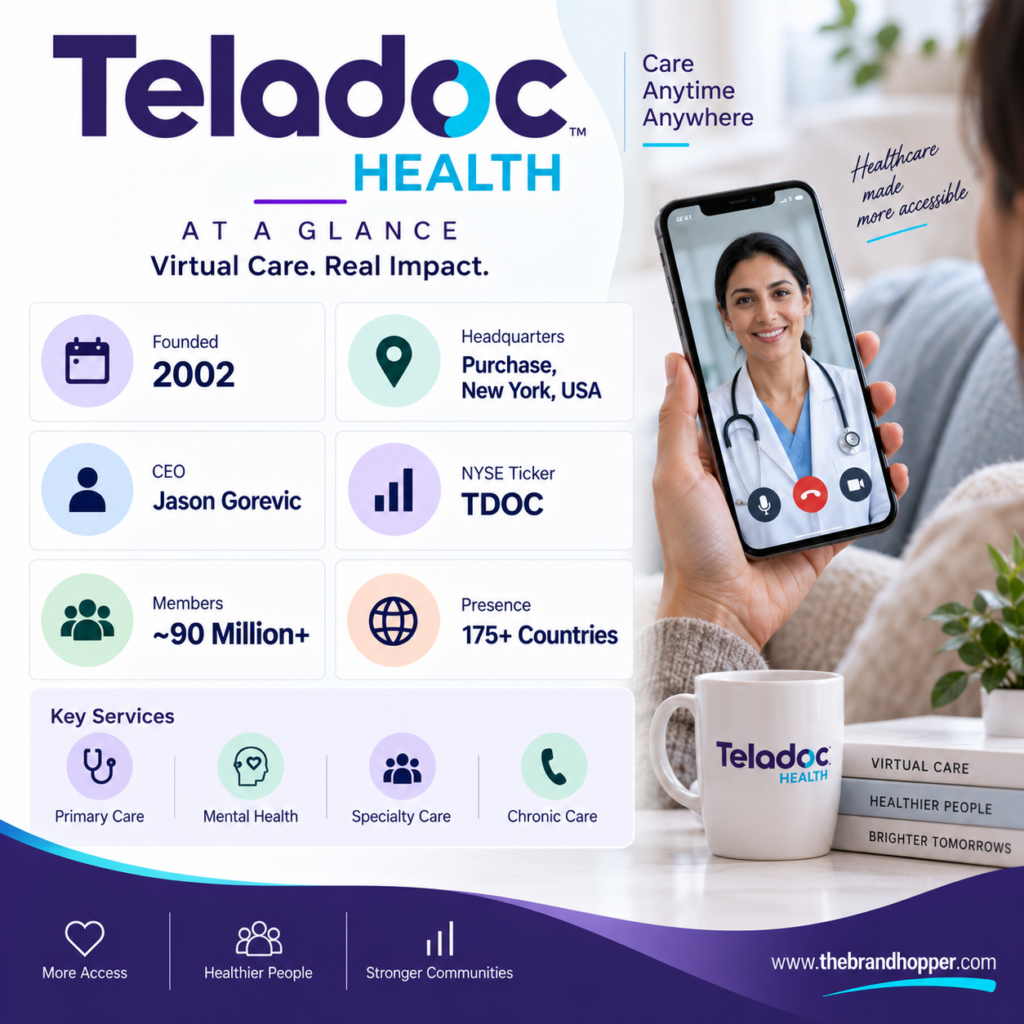
Website: https://www.teladochealth.com/
Teladoc Health is the world’s largest provider of virtual healthcare services. The company offers telehealth consultations across primary care, mental health (through BetterHelp), chronic disease management, and specialty care — services that directly compete with CVS’s MinuteClinic and, to a lesser extent, Oak Street Health’s primary care offering. Teladoc serves over 85 million members globally and generated approximately $2.6 billion in revenues in its most recently reported full year.
Teladoc’s most significant competitive overlap with CVS is in primary care access. MinuteClinic — which CVS has been consolidating from 1,150 to 875 locations — offers nurse practitioner-led care for acute conditions and preventive services. Teladoc offers a virtual equivalent: same-day consultations with physicians for the same conditions, without requiring the patient to leave home. As consumers became accustomed to telemedicine during the COVID-19 pandemic and have continued using it for convenience, the addressable patient volume for MinuteClinic has been partially absorbed by Teladoc and peers.
Teladoc also partners with many of the same employers and health plans that CVS serves through Caremark and Aetna, creating a situation where CVS and Teladoc simultaneously compete for patient care volume and co-exist within the same benefit ecosystems. The company has faced investor pressure following its $18.5 billion acquisition of Livongo Health in 2020, which was written down significantly. But its installed base and brand recognition in virtual care remain formidable competitive assets.
15. McKesson Corporation (Health Mart)
Website: https://www.mckesson.com
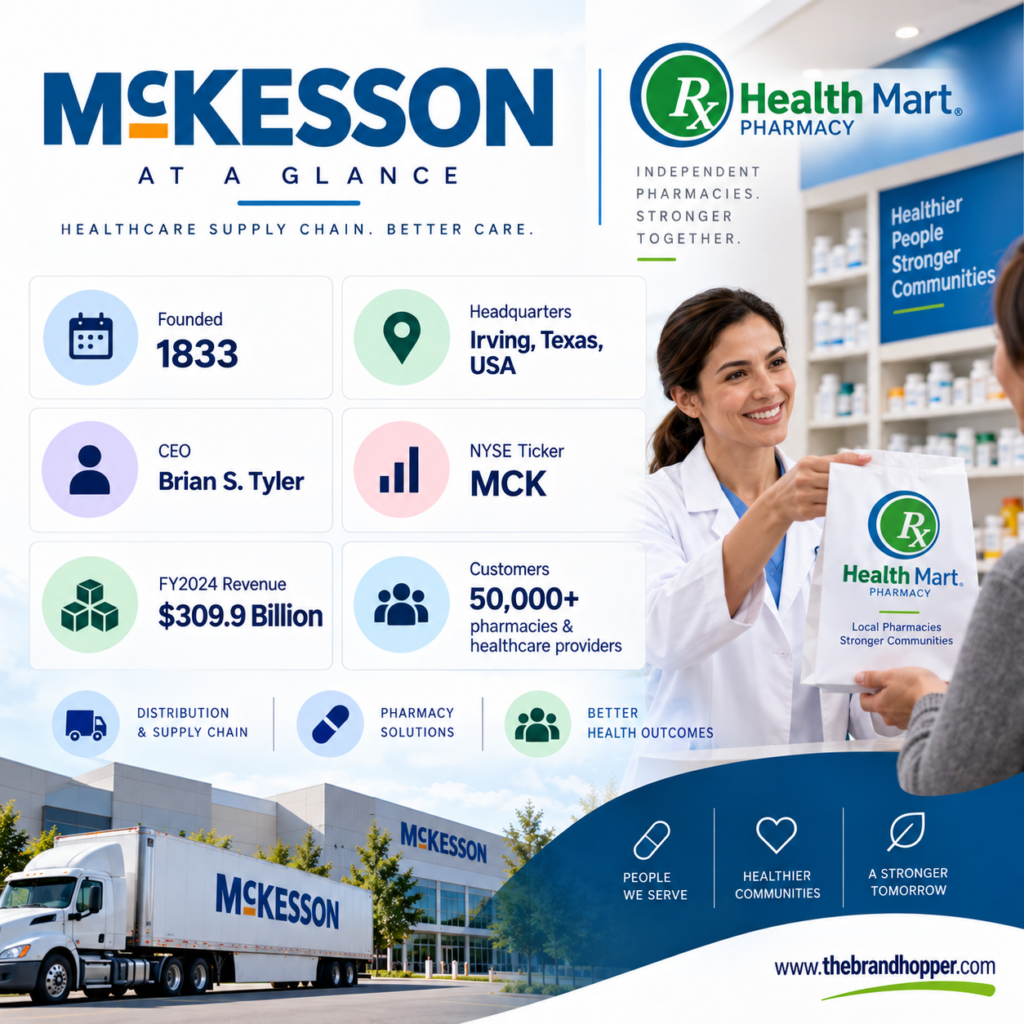
McKesson Corporation is primarily a pharmaceutical distribution company rather than a retail pharmacy chain, but its role in the competitive landscape around CVS Health is substantial. As one of the largest drug distributors in the United States, McKesson supplies medications to hospitals, retail pharmacies (including CVS and Walgreens), and specialty clinics. Its Health Mart subsidiary operates the largest network of independent community pharmacies in the US, with approximately 4,500 independently owned members.
Health Mart pharmacies are independently owned but benefit from McKesson’s group purchasing, generic drug sourcing, and technology infrastructure — giving them price competitiveness that standalone independents could not achieve alone. When consumers choose a local independent pharmacy over a CVS chain location, Health Mart’s network is often the infrastructure behind it. This makes McKesson a systemic competitor rather than a direct one: it does not own pharmacy locations, but it enables thousands of pharmacies to compete effectively with CVS at the community level.
McKesson’s 2022 acquisition of Capsule added digital pharmacy capabilities to its Health Mart playbook. The company’s pharmaceutical distribution revenues make it one of the largest companies in the United States by revenue. For CVS, the most relevant competitive dynamic with McKesson is not at the consumer level but at the supplier and market structure level: McKesson’s strength in independent pharmacy support constrains CVS’s ability to consolidate pharmacy market share in the many communities where independent pharmacies remain the patient’s preferred option.
16. Ro Health
Website: https://rohealth.com/
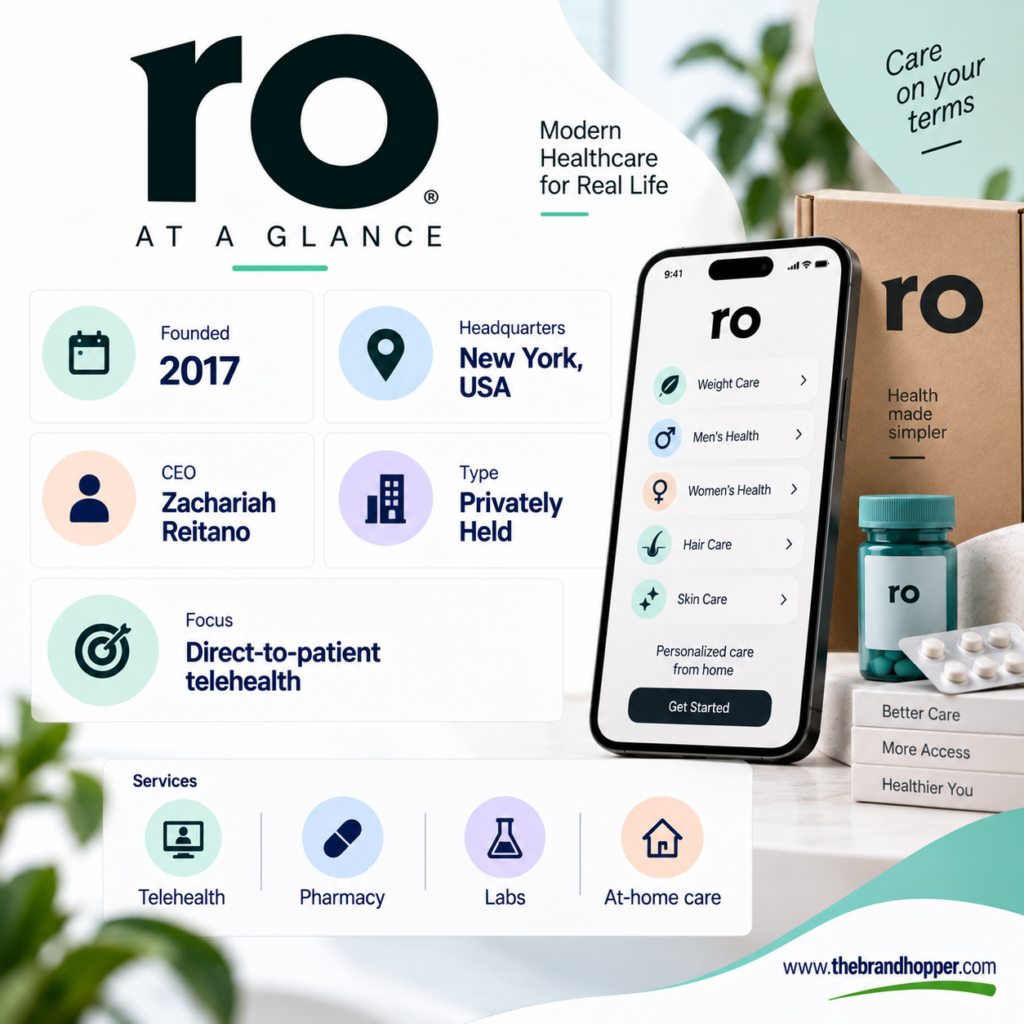
Ro (originally Roman) is a direct-to-consumer healthcare platform that combines licensed telehealth consultations with a licensed online pharmacy, offering treatments across erectile dysfunction, hair loss, fertility, and increasingly, weight management and GLP-1 prescriptions. The company operates pharmacies in multiple US states and has built a vertically integrated healthcare delivery model that competes directly with CVS’s combination of retail pharmacy and MinuteClinic walk-in care.
Ro’s growth has been significant in the GLP-1 category. Like Hims & Hers, Ro began offering compounded semaglutide injections in 2024, taking advantage of a period when branded GLP-1 drugs (Ozempic, Wegovy) faced supply shortages that placed them on the FDA’s drug shortage list, permitting compounding. Ro’s Body programme offers weight loss consultations, GLP-1 prescriptions, and ongoing clinical support in a subscription model that is faster, cheaper, and more convenient than obtaining a prescription through a traditional physician visit and filling it at a CVS.
Ro also operates Rho Pharmacy, its licensed dispensing pharmacy, which ships prescriptions directly to patients in most US states. This vertically integrated model — where consultation, prescription, dispensing, and ongoing support all happen within Ro’s platform without the patient visiting a physical location — represents the most consumer-centric version of the healthcare model that CVS’s Aetna + MinuteClinic + Caremark + CVS Pharmacy combination is trying to approximate at far greater scale and complexity.
The Future of the Pharmacy and Healthcare Competitive Landscape
The competitive map surrounding CVS Health will continue to evolve, shaped by four dominant forces.
PBM Reform: The pharmacy benefit management business model faces its most serious regulatory threat in decades. The FTC, congressional committees, and multiple state legislatures are investigating or legislating against practices like spread pricing, rebate retention, and formulary manipulation. CVS Caremark, OptumRx, and Express Scripts all derive significant revenue from practices that are under scrutiny. If PBM reform legislation passes, the financial model underlying much of CVS’s profitability will require fundamental restructuring.
GLP-1 and Weight Management: The explosive growth of GLP-1 medications (semaglutide, tirzepatide) is reshaping both pharmaceutical demand and the competitive dynamics of health services. GLP-1 drugs are among the most prescribed and most lucrative medications in the United States, and the battle over who fills, manages, and monitors GLP-1 prescriptions — traditional PBMs like Caremark, telehealth platforms like Hims & Hers and Ro, or direct-to-consumer services like Amazon Pharmacy — will be a defining competitive struggle for the next five years.
AI and Personalisation: Artificial intelligence is beginning to enable genuinely personalised medication management, adherence programmes, and clinical decision support at scale. UnitedHealth’s OptumInsight, Amazon’s data infrastructure, and digital-native platforms like Hims & Hers and Ro are all better positioned than legacy pharmacy chains to deploy AI in the customer experience layer. CVS’s investment in data analytics and its AI-enabled MinuteClinic programmes are steps in this direction, but the pace of AI adoption in healthcare is accelerating faster than any traditional incumbent can comfortably track.
Consolidation vs. Fragmentation: The market will simultaneously consolidate at the institutional level (large insurers and PBMs absorbing more of the value chain) and fragment at the consumer level (direct-to-consumer platforms capturing patients who prefer to bypass traditional systems). CVS sits uncomfortably in the middle of both dynamics. Its response — continuing to invest in Aetna, Oak Street Health, and the Caremark PBM while rationalising its retail pharmacy footprint — is a coherent strategic narrative, but execution risk and margin pressure remain the defining challenges of the next decade.
Frequently Asked Questions (FAQs)
Q1. Who is CVS Health’s biggest competitor?
A: In retail pharmacy, Walgreens Boots Alliance remains CVS Health’s closest direct competitor by store count and format, operating approximately 8,500 US locations. In pharmacy benefit management (PBM), CVS Caremark competes most directly with OptumRx (UnitedHealth Group) and Express Scripts (Cigna/Evernorth). In health insurance, Aetna’s most direct competitor is UnitedHealthcare, followed by Cigna, Humana, and Elevance Health. The competitive threat landscape is therefore multi-dimensional rather than having a single primary rival. Source: Company filings; industry analyses.
Q2. What happened to Rite Aid — is it still operating?
A: No. Rite Aid permanently closed all its stores by late 2025 following its second Chapter 11 bankruptcy filing in May 2025. The company had previously filed for bankruptcy in October 2023 and emerged in September 2024, but was unable to achieve financial stability at its reduced footprint of approximately 1,245 locations. After 60 years in operation, Rite Aid ceased trading entirely, with prescription files and some locations acquired by other pharmacy operators. Source: Axios; Bloomberg; Fox Business.
Q3. How does Amazon Pharmacy compete with CVS?
A: Amazon Pharmacy competes primarily on convenience and pricing. Amazon offers free two-day prescription delivery for Prime members, same-day delivery in an increasing number of US cities, and its RxPass subscription ($5/month for access to 60 generic medications). Amazon is estimated to have generated $1.25–2 billion in prescription revenues in 2024, with plans to expand same-day delivery to 20 additional cities in 2025. Amazon’s competitive advantage lies in its logistics infrastructure, Prime membership distribution, and customer experience — not in clinical services, where CVS’s MinuteClinic and Oak Street Health remain differentiated. Source: Forbes; AHIP 2024; Amazon corporate.
Q4. What is CVS Health’s revenue and how does it compare to competitors?
A: CVS Health reported $372.8 billion in total revenues for the full year 2024, making it one of the largest revenue-generating companies in the United States. By comparison, UnitedHealth Group — its largest competitor — reported $400.3 billion in 2024 revenues, making it slightly larger than CVS. Cigna Group reported $247.1 billion in 2024, Humana reported approximately $116.3 billion in premiums, and Elevance Health CarelonRx generated $33.8 billion. No other pharmacy or healthcare competitor currently matches CVS’s overall revenue scale. Source: Respective company earnings releases and SEC 10-K filings.
Q5. What are the new digital pharmacy competitors challenging CVS?
A: The most significant digital pharmacy competitors include: Amazon Pharmacy (prescription delivery with Prime logistics), Hims & Hers Health ($1.48 billion in 2024 revenue, specialising in telehealth + DTC pharmacy including GLP-1 weight loss), Ro Health (direct-to-consumer telehealth and licensed pharmacy, strong in GLP-1 category), Capsule (digital pharmacy experience acquired by McKesson/Health Mart), GoodRx (prescription price comparison with $771 million in 2024 revenues), and Mark Cuban’s Cost Plus Drugs (radically transparent pricing with $100 million+ estimated revenues). Each attacks a different weakness in the traditional CVS model. Source: Company filings; Fierce Healthcare; Forbes.
Q6. Why did Walmart close its health clinics and what does this mean for CVS?
A: Walmart closed all 51 Walmart Health clinics in April 2024, citing an unsustainable reimbursement environment and escalating operating costs. The failure underscores the structural difficulty of combining retail and primary care: insurance reimbursement rates for primary care services are often insufficient to cover the fixed costs of clinic operation at retail locations, particularly when staffed by physicians rather than nurse practitioners. Walmart continues to operate 4,600+ pharmacies. For CVS, Walmart’s exit from primary care has both reduced a potential future competitor in clinic-based care and validated the difficulty of the model CVS is pursuing through Oak Street Health. Source: Walmart corporate; CNBC; Healthcare Dive.
Q7. How is the GLP-1 drug boom affecting CVS and its competitors?
A: The GLP-1 prescription boom (Ozempic, Wegovy, Mounjaro) is one of the most significant drug category developments in decades. For CVS, GLP-1 drugs represent a major volume driver in both retail pharmacy (filling prescriptions) and Caremark PBM (managing coverage and utilisation for employer and health plan clients). However, the GLP-1 boom has also created a powerful direct-to-consumer channel through telehealth companies like Hims & Hers Health and Ro, which offer compounded semaglutide at significantly lower prices than the branded equivalents. Hims & Hers targets $725 million in weight loss revenues for 2025. This dynamic means GLP-1 drug growth benefits CVS’s volume but simultaneously accelerates competitor growth in the DTC pharmacy channel. Source: Fierce Healthcare; Hims & Hers investor relations.
Q8. What is CVS Health doing to maintain its competitive position?
A: Under CEO David Joyner (who replaced Karen Lynch in October 2024), CVS is executing a $2 billion cost-reduction programme focused on rationalising underperforming assets while investing in its core health services strategy. Key initiatives include: rationalising MinuteClinic from 1,150 to 875 locations to focus on the most productive sites; exiting underperforming Aetna Medicare Advantage markets where medical cost ratios are unsustainable; continuing to grow Oak Street Health (which has 230 centres across 27 states after closing 16 underperforming locations); expanding CarePass membership and CVS app digital engagement; and investing in CVS Caremark’s pharmaceutical manufacturer and specialty pharmacy relationships. Source: CVS Health investor presentations; Modern Healthcare; Forbes.
Also Read: From Retail Pharmacy to Healthcare Giant: Story of CVS Health
Conclusion
CVS Health’s competitive landscape has never been more complex or more consequential. The company operates at the intersection of retail pharmacy, pharmacy benefit management, health insurance, and primary care — each a battleground with distinct and formidable rivals. Walgreens is heading into private equity ownership with an uncertain future. UnitedHealth Group and Cigna’s vertically integrated health services models rival CVS in scale and strategic ambition. Amazon is capturing the convenience-focused prescription market one Prime member at a time. Hims & Hers, Ro, and Cost Plus Drugs are rethinking what pharmacy can look like without the PBM middle-layer. And Rite Aid’s collapse is a cautionary tale about what happens when scale, margin pressure, and debt collide.
For CVS, the path forward requires clarity about what kind of company it intends to be. Its $372.8 billion in revenue is impressive, but revenue does not equal strategic coherence. The company that acquired Aetna for $69 billion, Oak Street Health for $10.6 billion, and Signify Health for $8 billion is betting that the integrated health services model — where insurance, pharmacy, PBM, and primary care operate as a single system around the patient — creates durable competitive advantage. The early execution challenges, particularly in Aetna’s Medicare Advantage business, suggest the bet is harder to win than the acquisition rationale implied.
What is certain is that the industry CVS helped define — the American retail pharmacy — is being fundamentally disrupted. The question for CVS Health is not whether disruption is coming, but whether it can absorb, lead, or outrun it. With 10,000+ retail locations, 300,000+ employees, Aetna’s 40+ million members, Caremark’s 100+ million lives, and Oak Street Health’s 230 primary care centres, CVS has more levers to pull than nearly any competitor. Whether it pulls the right ones, in the right sequence, will determine whether it remains the centrepiece of American healthcare or becomes another institutional legacy overtaken by faster-moving rivals.
To read more content like this, subscribe to our newsletter